|
|
|
Daily Summary
|
September 29, 2026
|
Welcome to your daily digest. Today we are analyzing the latest income statements and filings from:
|
|
|
|
🔍 Deep Dive: Carnival Corp Ltd.
Period Ending 2026-08-31
|
|
🚨 Price Alert: The stock price jumped by 12.55% around the earning call.
|
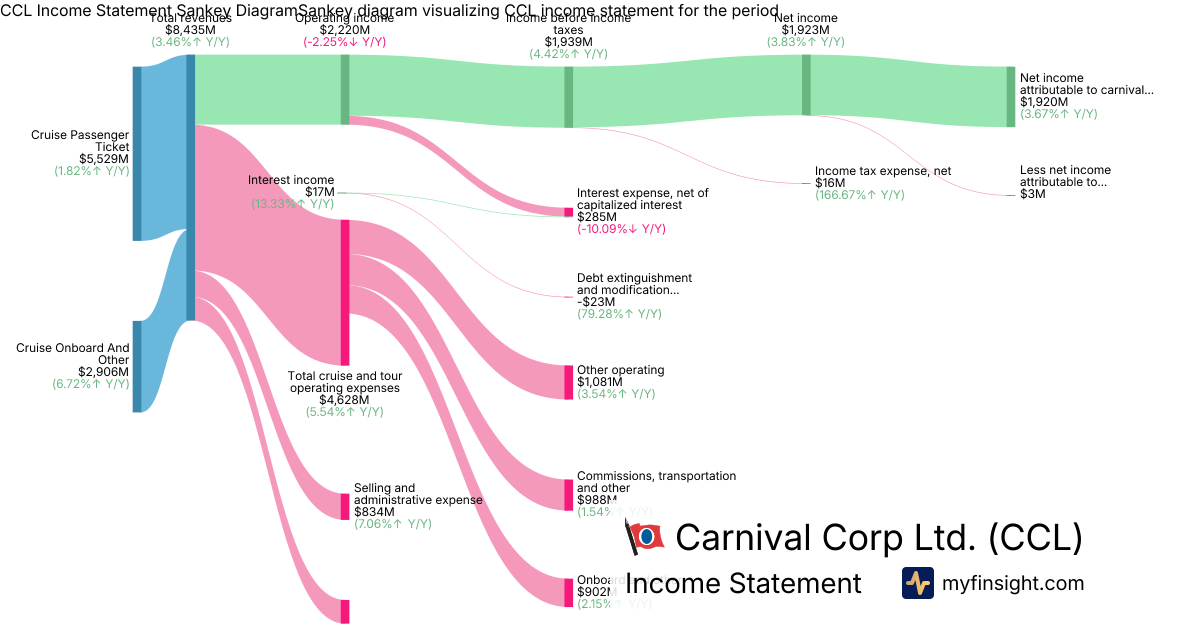
Carnival Corporation (CCL) has experienced notable price fluctuations around its recent earnings call, driven primarily by strong reported financial performance, particularly in revenue and net income, coupled with robust customer demand indicators. However, ongoing scrutiny of its substantial debt load and the inherent sensitivity of the cruise industry to macroeconomic conditions likely contributed to the "violent" swings as investors weighed both positive developments and potential headwinds.
Key Factors Contributing to Volatility:
- Strong Revenue and Profitability: Carnival reported significant financial improvements, with total revenues of $8.44 billion and net income attributable to Carnival Corporation of $1.92 billion. These strong figures likely fueled investor optimism regarding the company's post-pandemic recovery and operational efficiency.
- Robust Customer Demand and Future Bookings: A key indicator of future performance, customer deposits reached $7.13 billion, signaling strong demand and providing significant visibility into future revenue streams, which typically has a positive impact on stock performance.
- Significant Debt and Interest Expenses: While performance improved, the company continues to manage a substantial debt burden, with long-term debt at $21.9 billion and interest expense, net of capitalized interest, at $285 million. Investor reaction can be volatile based on management's outlook on debt reduction and the impact of rising interest rates.
- Operating Cost Management: High operating costs, including fuel expenses of $615 million and payroll and related costs of $641 million, are ongoing factors. Any indication of rising or falling operational efficiencies and cost pressures can significantly influence investor sentiment and stock price movements.
- Broader Economic and Industry Outlook: The cruise industry remains sensitive to global economic conditions, consumer discretionary spending, and geopolitical events. Concerns about potential economic slowdowns or shifts in travel trends can contribute to market uncertainty and exacerbate stock price volatility, even amidst positive company-specific news.
|
|
Revenue
$8.44B
|
|
Net Income
$1.92B
|
|
Net Margin
22.76%
|
|
🔍 Deep Dive: URANIUM ENERGY CORP
Period Ending 2026-07-31
|
|
🚨 Price Alert: The stock price dropped by 7.84% around the earning call.
|
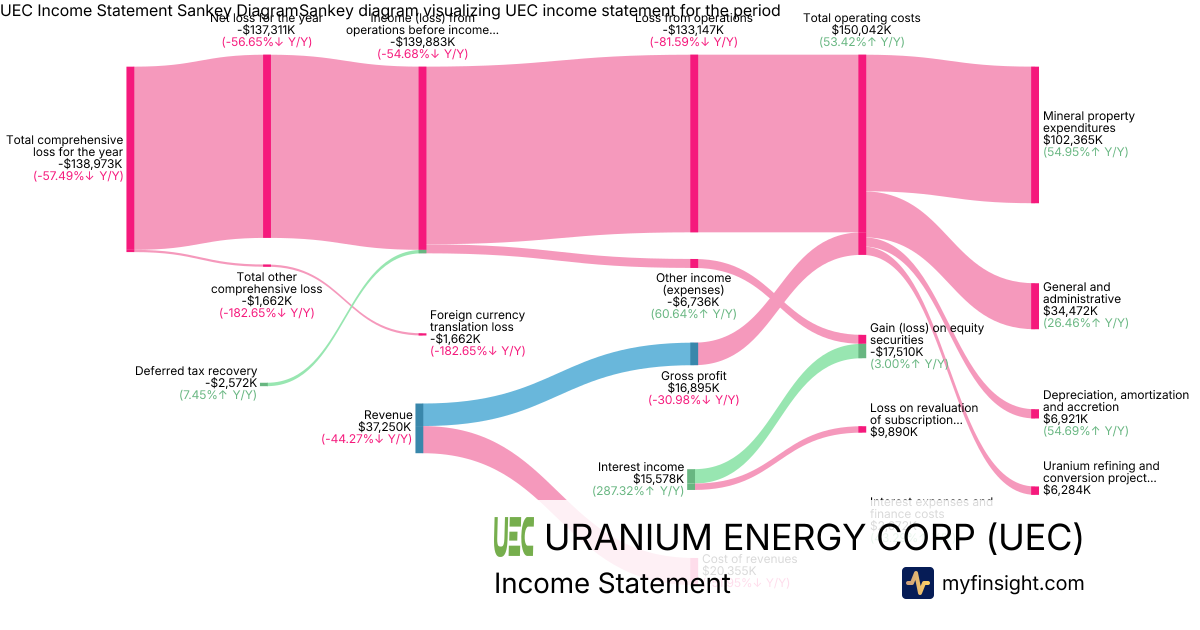
Uranium Energy Corp (UEC) has experienced significant price fluctuations around its recent earnings call due to a combination of strong operational improvements, a strategic market positioning, and a highly bullish outlook for the broader uranium sector, even as the company continues to report losses.
Key Factors Contributing to Volatility:
- Record Production and Improved Efficiency: UEC reported a substantial 157% increase in uranium production for the fourth quarter of fiscal 2026, alongside a 33% reduction in total costs per pound, signaling enhanced operational efficiency as it transitions into a multi-mine producer.
- Strategic Unhedged Sales and High Realized Prices: The company maintained an unhedged sales strategy, realizing a weighted average uranium price of $93.13 per pound for fiscal 2026, which it believes is among the highest for publicly traded uranium producers, and strategically built an inventory of 1.26 million pounds to capitalize on anticipated market strengthening. This strategy positions UEC to benefit from rising uranium prices.
- Robust Financial Position: UEC ended fiscal 2026 with a strong balance sheet, boasting $495 million in cash and a total of $753 million in liquid assets, with no debt, providing significant financial flexibility.
- Bullish Uranium Market Trends: The broader uranium market is experiencing strong tailwinds, with long-term contract prices reaching an 18-year high of $94/lb by mid-2026, driven by surging nuclear demand, government policies promoting nuclear energy for security and decarbonization, and an existing structural supply deficit.
- Mixed Earnings Report and Growth Expectations: While UEC missed analyst EPS estimates for Q4 fiscal 2026 with a net loss of -$137 million for the year, it exceeded revenue expectations with $37.3 million in full-year revenue. Analysts remain bullish on the stock, projecting significant future growth despite current unprofitability, as evidenced by an elevated Price-to-Sales (P/S) ratio.
|
|
Revenue
$37.2M
|
|
Net Income
-$139M
|
|
Net Margin
-373.08%
|
|
🔍 Deep Dive: COPART INC
Period Ending 2026-07-31
|
|
🚨 Price Alert: The stock price dropped by 6.12% around the earning call.
|
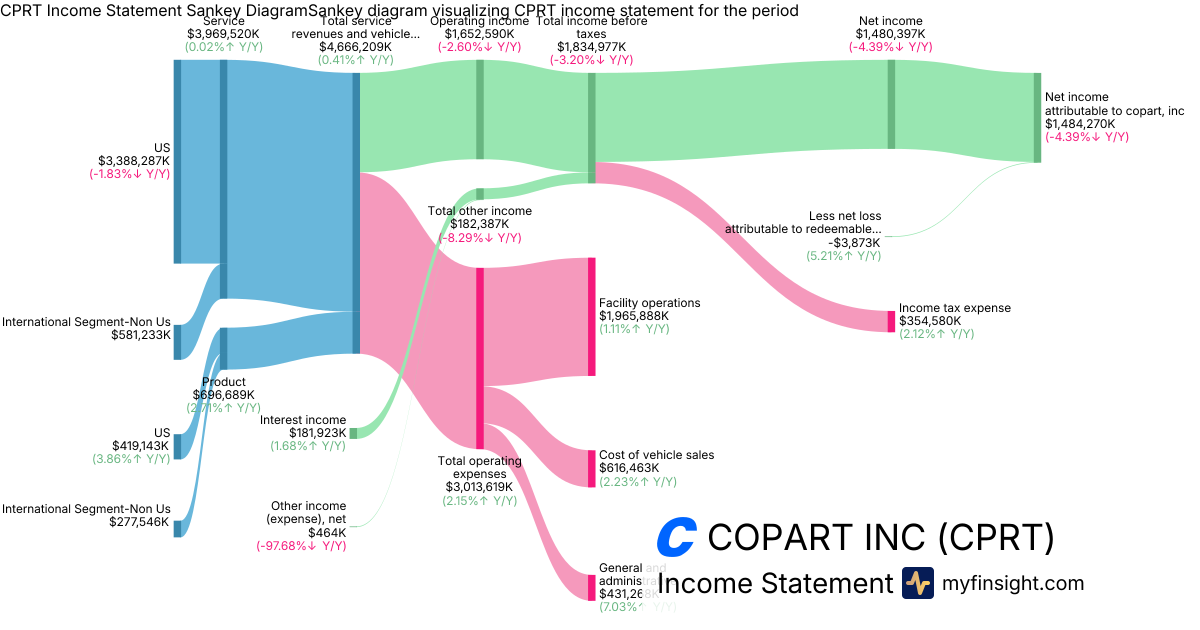
Copart (CPRT) has recently experienced notable price fluctuations around its latest earnings call, primarily driven by a combination of a significant earnings miss, increased operating expenses, a strategic acquisition, and a decline in domestic vehicle volumes.
Key Factors Contributing to Volatility:
- Q4 2026 Earnings Miss and Elevated Expenses: Copart reported Q4 2026 revenue of $1.2 billion, which fell short of analyst expectations, while net income decreased 17.4% to $327.4 million, and diluted earnings per share (EPS) of $0.35 missed the consensus estimate of $0.38. This was compounded by a 12.7% rise in operating expenses per unit, impacting overall profitability and gross margins.
- Strategic Acquisition of ACV Auctions: The announcement of an all-cash acquisition of ACV Auctions for $1.9 billion, while intended to enhance scale and technology in the digital automotive marketplace, introduced concerns among investors regarding integration risks and potential dilution.
- Decline in Domestic Vehicle Volumes: The company saw a 2.9% decline in global unit sales, with domestic insurance volumes falling 7.5%. This was partly due to the loss of a major national insurance account to a competitor, though international growth offered some offset.
- CEO Stock Sale and Mixed Analyst Sentiment: The sale of 27,745 shares by CEO Jeffrey Liaw contributed to investor caution. Furthermore, despite some analyst upgrades, the stock hitting a new 52-week low and mixed market sentiment reflected ongoing concerns about near-term operational challenges.
- Full-Year Financial Performance: For the full fiscal year 2026, Copart reported total service revenues and vehicle sales of $4.67 billion, which was flat year-over-year, and net income attributable to Copart, Inc. declined 4.4% to $1.48 billion. The company's cash, cash equivalents, and restricted cash also decreased to $1.91 billion, influenced by share buybacks and investments.
|
|
Revenue
$4.67B
|
|
Net Income
$1.48B
|
|
Net Margin
31.81%
|
|
This newsletter is sent from
MyFinsight.com.
Was this email forwarded to you? Sign up here.
Unsubscribe
Copyright © 2026 MyFinsight, All rights reserved.
|