🔗 PEPSICO INC, 🔗 LEVI STRAUSS & CO, 🚨 CONSTELLATION BRANDS, INC., 🔗 CINTAS CORP
|
|
|
Daily Summary
|
October 08, 2026
|
Welcome to your daily digest. Today we are analyzing the latest income statements and filings from:
|
|
|
|
🔍 Deep Dive: PEPSICO INC
Period Ending 2026-09-05
|
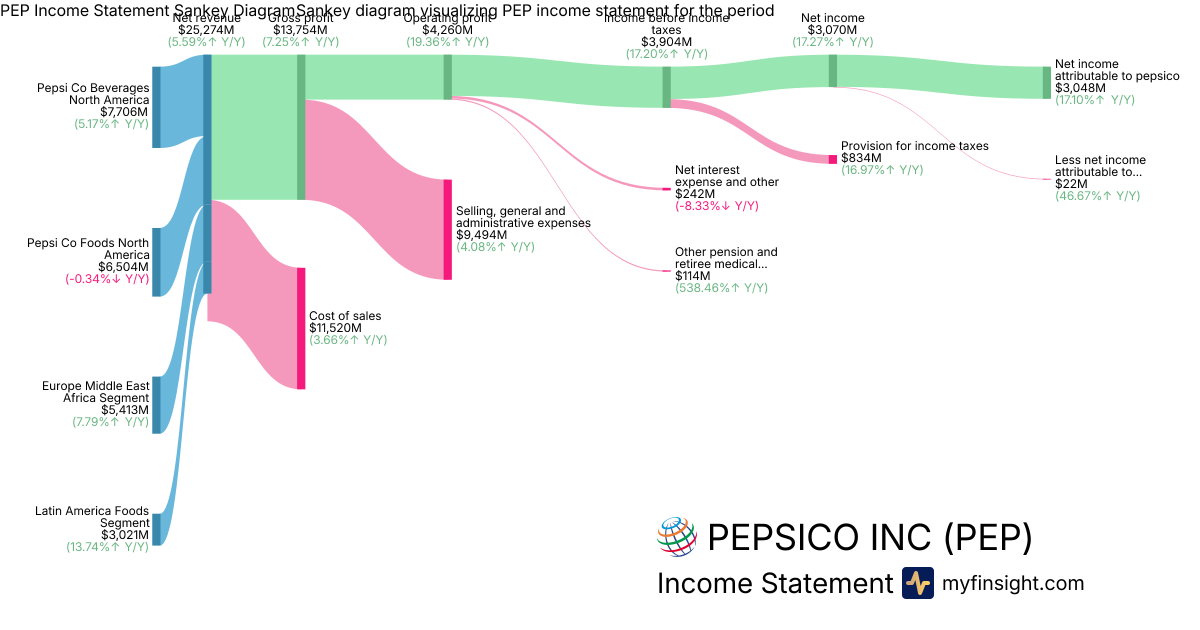
- Strong Q3 Performance with Revenue Beat: PepsiCo reported net revenue of $25.3 billion, surpassing analyst expectations and marking a 5.6% year-over-year increase. Net income attributable to PepsiCo was $3.05 billion, with organic revenue growing 3.1%, the fastest pace since Q4 2023.
- Revised Full-Year Profit Guidance: Despite the strong top-line performance, management trimmed its full-year core EPS growth forecast to 2.5% to 3.5% (1% to 2% on a constant-currency basis) from an earlier higher outlook. This revision was primarily attributed to higher input costs, unfavorable mix, and weaker-than-expected North American beverage performance.
- International Markets as a Key Growth Driver: International operations continued to be a significant bright spot, with organic revenue growing 8% and operating margin expanding by approximately 105 basis points. Key international segments like Europe, Middle East, and Africa contributed $5.41 billion in revenue, Latin America Foods $3.02 billion, and Asia Pacific Foods $1.23 billion.
- North American Business Challenges: While PepsiCo Foods North America showed some improvement in snacks volume, contributing $6.5 billion in revenue, the North American beverages segment experienced deceleration and remained a drag, generating $7.71 billion in revenue.
- Operating Margin Pressure: Core operating profit increased 3% to $4.26 billion, but the core operating margin narrowed by approximately 35-40 basis points to 16.9%. This was primarily due to higher input costs and an unfavorable mix, although partially offset by productivity savings and revenue management efforts.
Overall Takeaway
The Q3 fiscal 2026 earnings call for PepsiCo was broadly neutral to cautiously positive. While the company demonstrated robust net revenue growth and exceeded analyst expectations for the quarter, largely driven by strong performance in international markets, the downward revision of the full-year profit outlook due to cost pressures and softness in North American beverages introduces a note of caution for investors. The results indicate a resilient core business, but with ongoing challenges requiring diligent management.
|
|
Revenue
$25.3B
|
|
Net Income
$3.05B
|
|
Net Margin
12.06%
|
|
🔍 Deep Dive: LEVI STRAUSS & CO
Period Ending 2026-08-30
|
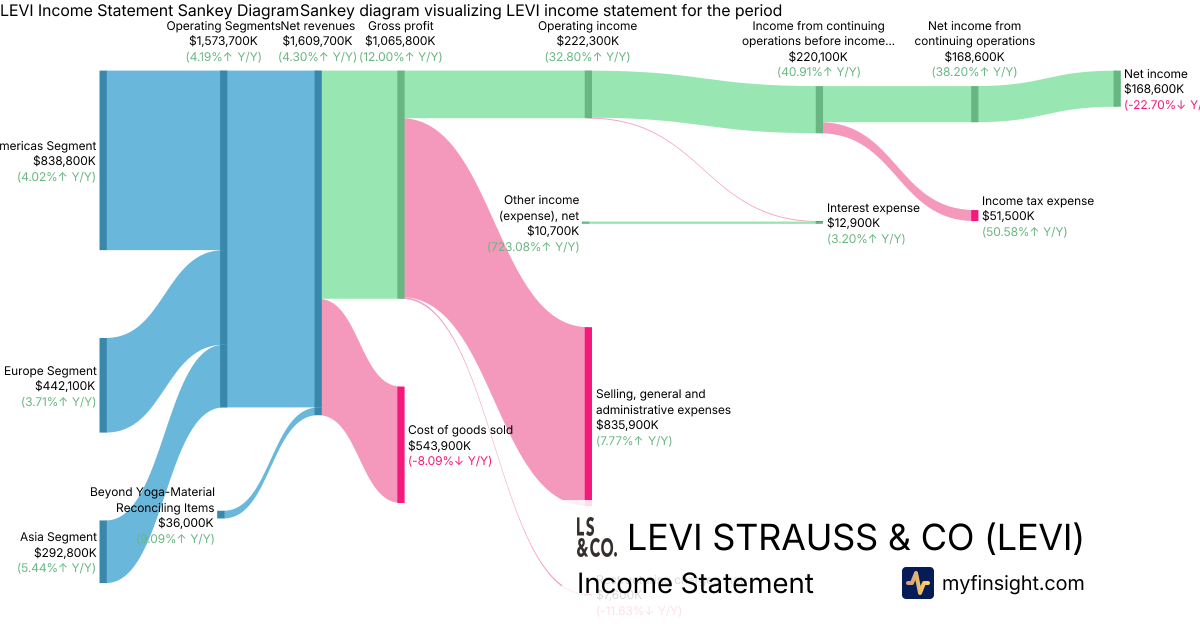
- Solid Revenue and EPS Beat: Levi Strauss & Co. reported $1.61 billion in net revenues for Q3 fiscal 2026, marking a 4% reported increase and 5% organic growth. The company also delivered adjusted diluted EPS of $0.48, significantly beating analyst expectations.
- Gross Margin Expansion Driven by Tariff Refunds: Gross margin expanded by 450 basis points to 66.2%, largely benefiting from approximately $80 million in tariff refunds, which contributed 370 basis points to the expansion.
- Mixed Channel Performance: Global wholesale revenue increased by 6%, showing growth across all segments, and international business grew 8%, led by Asia's double-digit growth for the third consecutive quarter. However, global Direct-to-Consumer (DTC) sales grew only 2%, with flat comparable sales, particularly impacted by softer traffic in the U.S. and Europe.
- Strategic Investments and Outlook: Management acknowledged the DTC weakness and plans to redeploy a portion of the tariff refund benefits into marketing investments and supply chain capabilities to support holiday season demand. The company reiterated its full-year organic revenue growth guidance of approximately 6% and adjusted diluted EPS in the range of $1.54 to $1.56.
- Inventory Management and Shareholder Returns: Inventory levels were reported down by 3%. The company also returned $62 million to shareholders via dividends, an 11% year-over-year increase, and announced an additional $100 million accelerated share repurchase program.
Overall Takeaway
The Q3 fiscal 2026 earnings call for LEVI was **broadly positive**, driven by strong adjusted EPS that exceeded expectations and significant gross margin expansion due to tariff refunds and lower product costs. While the company demonstrated robust performance in its wholesale and international segments, particularly in Asia, softer Direct-to-Consumer traffic in the U.S. and Europe presented a noted challenge. Management outlined plans to address these areas through strategic investments, signaling a proactive approach to maintain growth and profitability despite some headwinds.
|
|
Revenue
$1.61B
|
|
Net Income
$169M
|
|
Net Margin
10.47%
|
|
🔍 Deep Dive: CONSTELLATION BRANDS, INC.
Period Ending 2026-08-31
|
|
🚨 Price Alert: The stock price jumped by 9.35% around the earning call.
|
Constellation Brands (STZ) has experienced significant price fluctuations around its recent earnings call due to a combination of strong second-quarter performance being tempered by cautious forward guidance, alongside persistent macroeconomic headwinds affecting consumer spending in its key beverage alcohol segments.
Key Factors Contributing to Volatility:
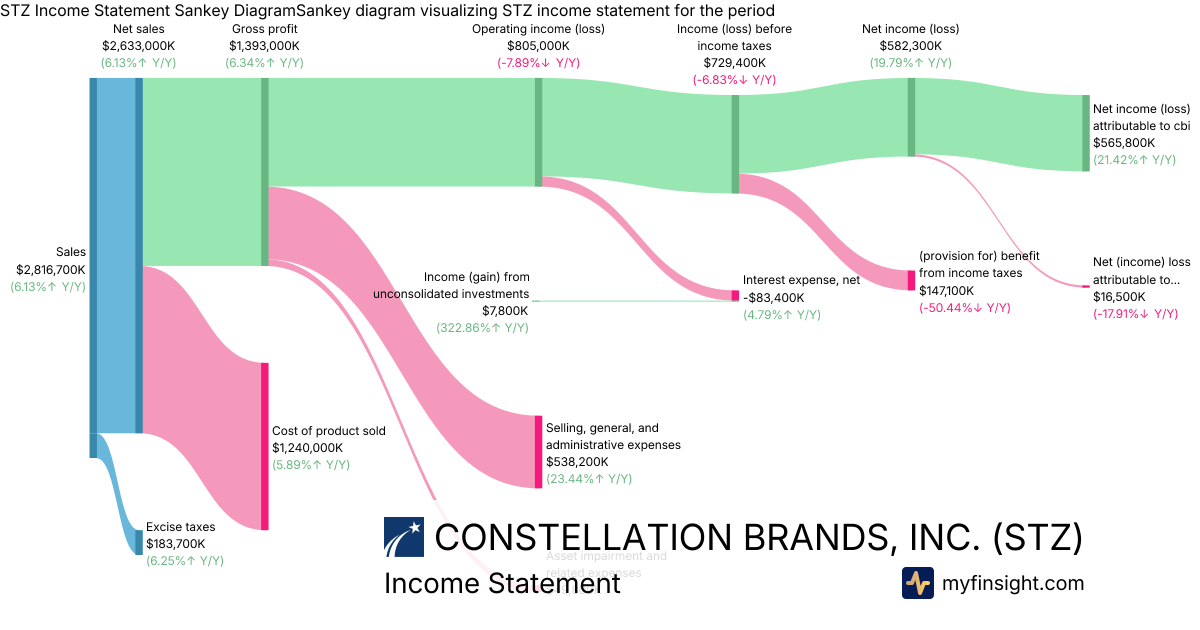
- Strong Q2 Performance vs. Conservative Outlook: STZ reported robust second-quarter fiscal year 2027 results, with
net sales reaching $2.63 billion, surpassing analyst estimates, and
net income attributable to CBI increasing to $566 million. However, the company maintained its full-year guidance rather than raising it, implying a softer second half and leading to investor uncertainty.
- Mixed Beer Segment Dynamics: While the Beer segment remains a growth driver with
net sales of $2.47 billion, a decline in depletions (sales to consumers) for core brands like Modelo Especial and Corona Extra indicated a slowdown in consumer demand, particularly among Hispanic populations, despite an increase in shipments (sales to distributors) due to inventory adjustments.
- Operating Margin Pressure: The Beer segment's operating margin contracted by 160 basis points to 39%, influenced by factors such as unfavorable fixed cost absorption, increased Cost of Goods Sold (COGS) including aluminum tariffs, and higher marketing investments. Overall,
operating income for the quarter was $805 million, down 8% year-over-year.
- Strategic Long-Term Investments: Constellation Brands continues to pursue aggressive long-term capacity expansion for its beer business, betting on future demand despite current macroeconomic headwinds and subdued consumer spending, which introduces a blend of long-term optimism and short-term financial strain. The company's
long-term debt stands at $9.1 billion, reflecting significant ongoing investments.
- Undervaluation and Analyst Sentiment: Despite the operational challenges and guidance concerns, several analyses suggest that STZ stock is currently undervalued relative to its historical performance, trading at a P/E ratio significantly below its five-year median. This perceived undervaluation, alongside a consensus "Hold" rating from analysts and significant upside potential in price targets, contributes to the stock's volatility as investors weigh risks and opportunities.
|
|
Revenue
$2.63B
|
|
Net Income
$566M
|
|
Net Margin
21.49%
|
|
🔍 Deep Dive: CINTAS CORP
Period Ending 2026-08-31
|
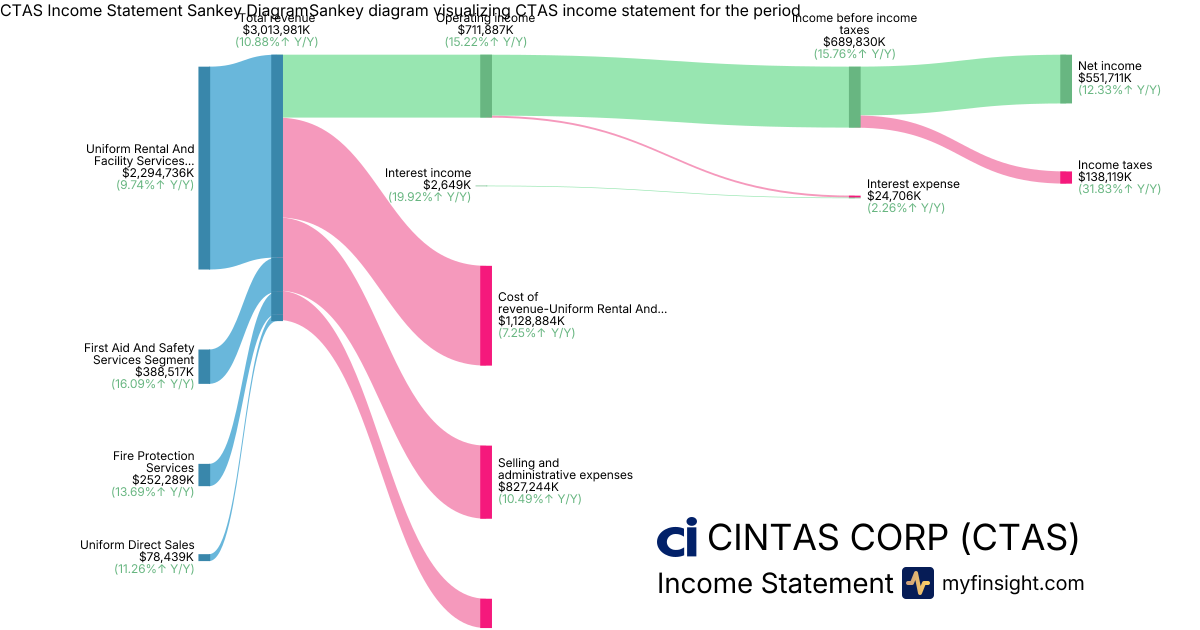
- Strong Q1 FY2027 Performance: Cintas reported Q1 FY2027 revenue of $3.01 billion, a 10.9% increase year-over-year and the first time the company exceeded $3 billion in a quarter. Diluted earnings per share (EPS) was $1.36, with adjusted diluted EPS reaching $1.39, surpassing analyst estimates. Operating income increased 15.2% to $711.9 million, driving a record operating margin of 23.6%.
- Raised Fiscal 2027 Guidance: Management updated its FY2027 guidance, raising expected revenue to $12.15 billion - $12.27 billion (representing 7.9% to 8.9% growth) and adjusted diluted EPS to $5.45 - $5.54 (implying 10.3% to 12.1% growth). This revised outlook reflects confidence in continued demand and projects incremental margins to improve to 32%-34%.
- Broad-Based Organic Growth Drivers: The company achieved 8.9% organic revenue growth, primarily attributed to strong demand for outsourced services, new customer acquisitions (especially from "no-programmers" who previously managed services in-house), improved customer retention, and effective cross-selling. Notably, the Uniform Rental and Facility Services segment saw 8.0% organic growth, while First Aid and Safety Services grew organically by 14.2%.
- Operational Efficiency and Shareholder Returns: Operational efficiency gains, driven by automation and technology investments like the SmartTruck platform, helped offset inflationary pressures. Cintas demonstrated a balanced capital allocation strategy by increasing its quarterly dividend by 15.6% (marking the 43rd consecutive year of increases) and repurchasing $545 million in shares through the date of the call.
- UniFirst Acquisition Update: The proposed acquisition of UniFirst Corporation is still awaiting regulatory clearance and is anticipated to close by the end of calendar 2026. Transaction expenses of $14.4 million related to this acquisition impacted reported EPS for the quarter.
Overall Takeaway
The Q1 fiscal 2027 earnings call for Cintas was broadly positive. The company delivered strong financial results that exceeded expectations, driven by robust organic growth across its segments and record operating margins. Management's decision to raise full-year guidance for both revenue and adjusted EPS, alongside a significant dividend increase and ongoing share repurchases, signals strong confidence in future performance despite costs associated with the UniFirst acquisition.
|
|
Revenue
$3.01B
|
|
Net Income
$552M
|
|
Net Margin
18.31%
|
|
This newsletter is sent from
MyFinsight.com.
Was this email forwarded to you? Sign up here.
Unsubscribe
Copyright © 2026 MyFinsight, All rights reserved.
|