🔗 CLEVELAND-CLIFFS INC., 🚨 General Motors Co, 🔗 RTX Corp, 🔗 GENERAL ELECTRIC CO, 🔗 PEGASYSTEMS INC
|
|
|
Daily Summary
|
October 20, 2026
|
Welcome to your daily digest. Today we are analyzing the latest income statements and filings from:
|
|
|
|
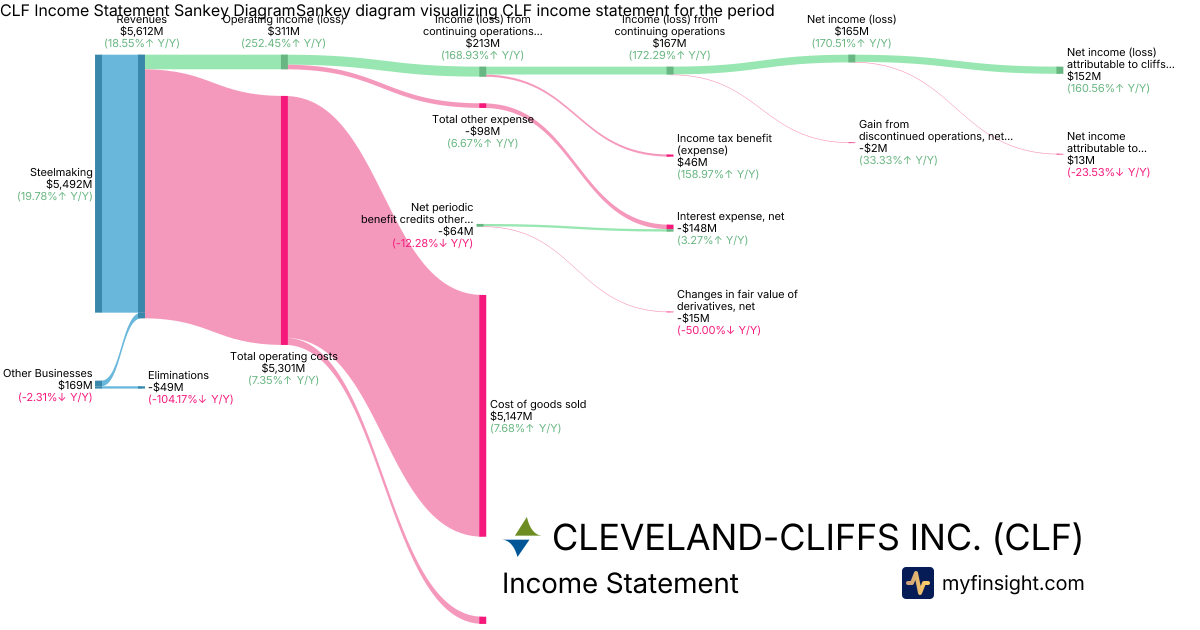
🔍 Deep Dive: CLEVELAND-CLIFFS INC.
Period Ending 2026-09-30
|
- Strong Q3 Performance and Exceeded Guidance: Cleveland-Cliffs reported third-quarter revenues of $5.6 billion and GAAP net income of $165 million, marking the strongest quarter in three years and exceeding adjusted EBITDA guidance. This improvement was driven by higher shipments, stronger average selling prices of $1,177 per ton, and lower unit costs.
- Robust 2027 Outlook and Contract Renewals: The company expects Q4 adjusted EBITDA to further increase to approximately $715 million, and projects 2027 adjusted EBITDA to exceed $4 billion, making it potentially the strongest year since 2021. Management anticipates over $1 billion in year-over-year EBITDA improvement from 2027 contract renewals, with many customers seeking more contracted volume.
- Prioritized Debt Reduction and Leverage Target: Cleveland-Cliffs remains focused on debt reduction, aiming to achieve a net leverage target of below 2.5x net debt to EBITDA by mid-2027, supported by amplified free cash flow and property sale proceeds.
- Strategic Investments and Operational Adjustments: Key strategic initiatives include the $1 billion modernization project at Middletown Works, partially funded by $500 million from the Department of Energy, and a 25% capacity expansion for grain-oriented electrical steel. The Burns Harbor C-blast furnace reline has been postponed to April 2028 to capitalize on favorable market conditions.
- Favorable Market Dynamics and Contract Structure: A supportive trade environment continues, with imports significantly below pre-Section 232 tariff levels. The company has implemented a "take or pay" structure for minimum tonnage in over 55% of new customer contracts and secured rollover pricing for 2027 coal contracts, providing stability in raw material costs.
Overall Takeaway
The earnings call was broadly positive. Cleveland-Cliffs demonstrated strong financial recovery in Q3, outperforming expectations, and provided an optimistic outlook for Q4 and 2027 driven by favorable market conditions, strategic contract renewals, and a disciplined approach to debt reduction. Management's commentary on trade protections, operational efficiency, and capital allocation further bolstered confidence in future performance.
|
|
Revenue
$5.61B
|
|
Net Income
$152M
|
|
Net Margin
2.71%
|
|
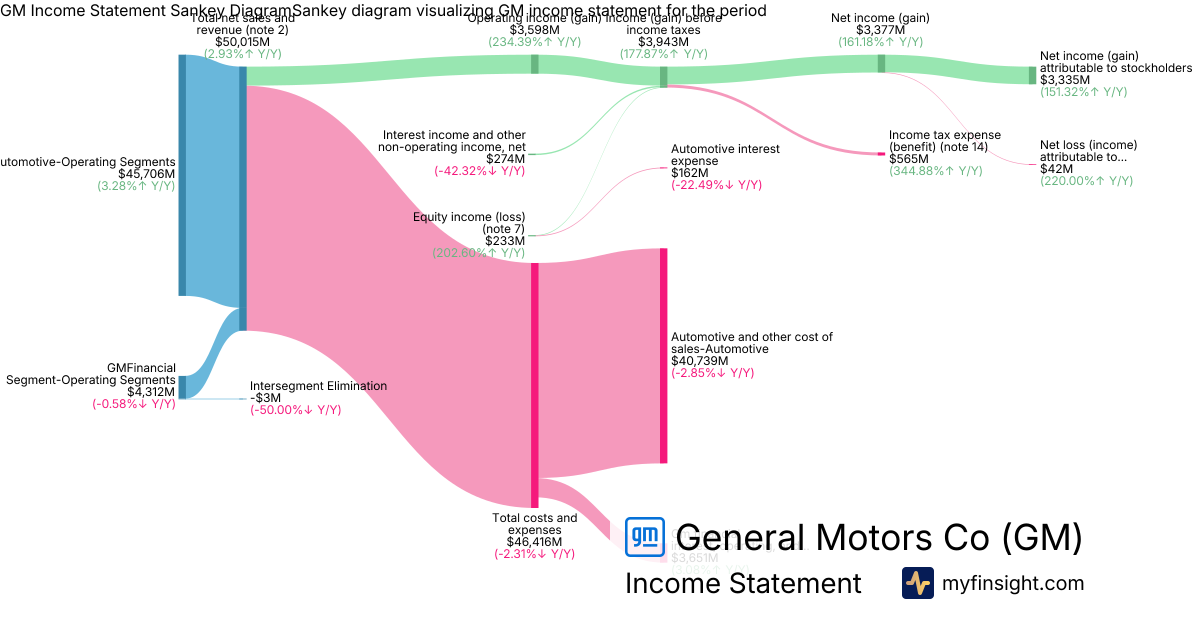
🔍 Deep Dive: General Motors Co
Period Ending 2026-09-30
|
|
🚨 Price Alert: The stock price dropped by 6.41% around the earning call.
|
General Motors (GM) recently experienced significant stock price fluctuations following its Q3 2026 earnings call. While the company delivered a strong beat on quarterly financial results, concerns over its narrowed full-year guidance and rising cost pressures appear to be the primary drivers of this volatility.
Key Factors Contributing to Volatility:
- Robust Q3 Performance: GM reported record quarterly revenue of $50.0 billion, surpassing analyst estimates. The company also posted a strong adjusted diluted earnings per share of $3.70 and an adjusted operating income (EBIT) of $4.1 billion, with a net income of $3.38 billion. This strong performance was largely driven by its North American operations, which achieved an adjusted EBIT of $3.6 billion and an 8.7% margin.
- Disappointing Full-Year Guidance: Despite the strong Q3, GM narrowed its full-year 2026 adjusted EBIT guidance and its adjusted EPS midpoint fell slightly below Wall Street expectations, leading to investor disappointment and a stock decline.
- Rising Cost Pressures: Concerns about intensifying commodity inflation, including record copper levels and high hot-rolled coil steel prices, are expected to add significant costs, further dampening the outlook.
- Slowing EV Demand and Production Adjustments: The company reported a 62% drop in Q3 EV sales and announced plans to cut Chevrolet Bolt EV production, reflecting a challenging electric vehicle market and strategic adjustments in its EV rollout. Furthermore, GM anticipates a fourth-quarter production downshift for newer models, resulting in fewer full-size pickup sales.
- Shareholder Returns Amidst Uncertainty: GM authorized a new $20 billion share repurchase program and raised its full-year adjusted automotive free cash flow guidance. While this indicates management's confidence, the market's focus remained on the cautious outlook and cost headwinds.
|
|
Revenue
$50B
|
|
Net Income
$3.33B
|
|
Net Margin
6.67%
|
|
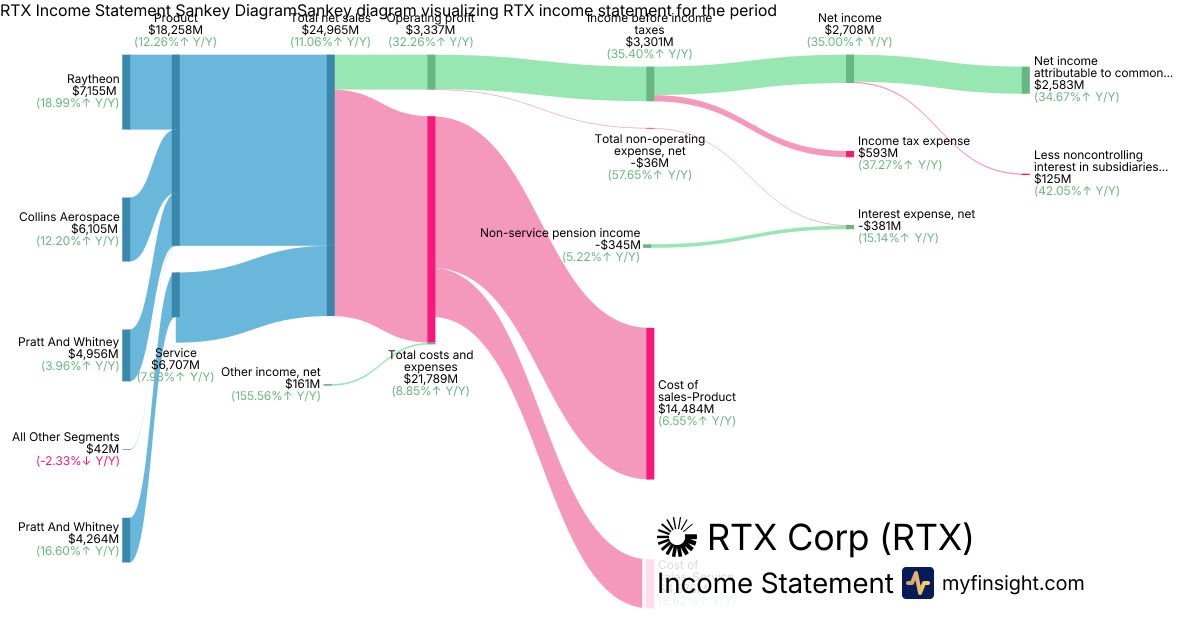
🔍 Deep Dive: RTX Corp
Period Ending 2026-09-30
|
- Strong Q3 Performance: RTX reported robust Q3 2026 results, with total sales of $25.0 billion, up 11% year-over-year and 12% organically, surpassing analyst estimates. Adjusted earnings per share reached $2.26, a 33% increase from the prior year, also beating expectations.
- Raised Full-Year Guidance: The company increased its full-year 2026 outlook for adjusted sales to $97.0 - $97.5 billion (previously $95.0 - $96.0 billion) and adjusted EPS to $7.65 - $7.75 (up from $7.10 - $7.25), along with a higher free cash flow target of $9.0 - $9.2 billion.
- Record Backlog and Defense Strength: RTX achieved a record company backlog of $340 billion, driven by strong demand and over $81 billion in new commercial and defense awards. Defense bookings were a significant contributor, with Raytheon securing nearly $59 billion in awards, including multi-year production contracts for Tomahawk and AMRAAM missiles. Raytheon's sales were $8.03 billion, up 14% year-over-year.
- Broad-Based Segment Growth: All three primary segments — Collins Aerospace, Pratt & Whitney, and Raytheon — demonstrated double-digit organic sales growth. Collins benefited from higher aircraft production rates, Pratt & Whitney saw continued momentum in GTF engine services and deliveries, and Raytheon experienced strong demand for its munitions and missile systems.
- Strategic Focus and Future Outlook: Management emphasized a focus on increasing output, optimizing the cost structure, and investing in new technologies to support customers and drive continued growth. Long-term contracts, particularly in defense, provide Raytheon with nearly a decade of demand visibility and potential for margin expansion.
Overall Takeaway
The Q3 2026 earnings call for RTX was broadly positive. The company delivered stronger-than-expected financial results, driven by robust demand across its commercial aerospace and defense segments. The significant increase in full-year guidance for sales, EPS, and free cash flow, coupled with a record-high backlog, signals strong operational momentum and positive future performance despite a mixed macro environment.
|
|
Revenue
$25B
|
|
Net Income
$2.58B
|
|
Net Margin
10.35%
|
|
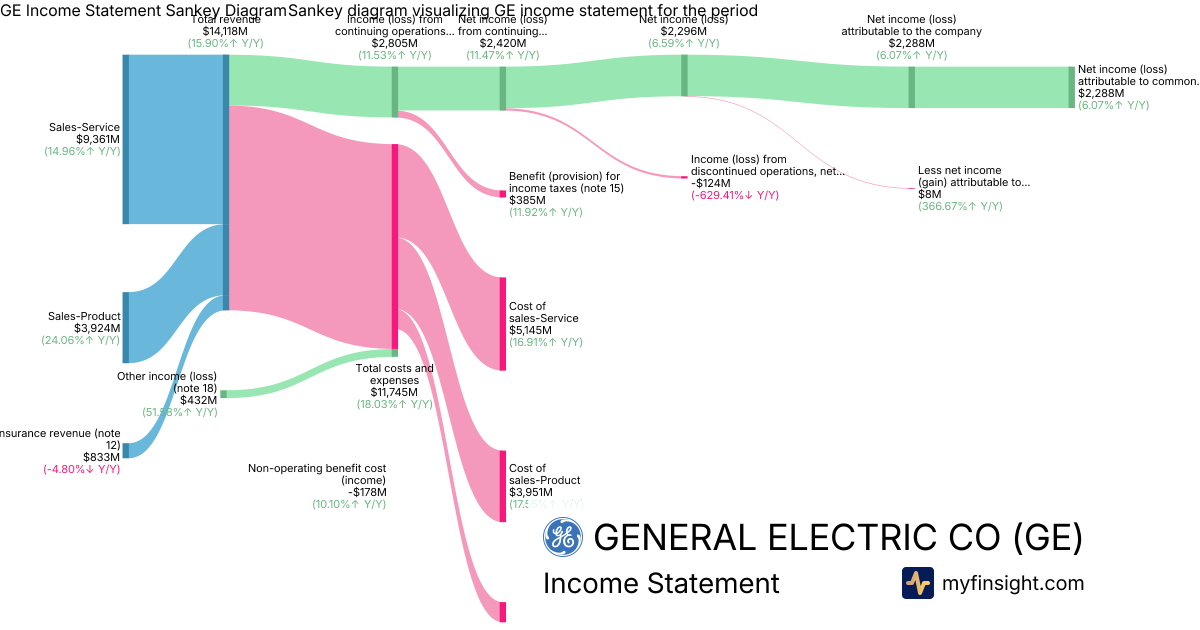
🔍 Deep Dive: GENERAL ELECTRIC CO
Period Ending 2026-09-30
|
- Strong Q3 Performance and Raised Guidance: GE Aerospace reported robust third-quarter GAAP revenue of $14.1 billion and GAAP profit of $2.81 billion, surpassing analyst expectations. The company raised its full-year 2026 guidance for adjusted revenue growth to 19%-20%, operating profit to $10.9 billion-$11 billion, and adjusted EPS to $8.00-$8.10.
- Significant Order Surge and Robust Backlog: Orders surged 49% year-over-year in Q3, driven by a 58% increase in commercial engines and services demand, contributing to a substantial total backlog of over $170 billion, providing strong visibility for future performance.
- Continued Commercial Engine Services Momentum: Commercial Engines & Services (CES) revenue grew 21%, marking the sixth consecutive quarter of at least 20% growth, with significant contributions from services (up 17%), spare parts (up over 20%), and equipment revenue (up 38%).
- Healthy Balance Sheet and Liquidity: The company demonstrated a strong financial position with total assets of $127 billion and total liabilities of $109 billion. Cash, cash equivalents, and restricted cash stood at $8.76 billion, supporting manageable long-term borrowings of $17 billion.
- Strategic Focus Amidst Market Nuances: Despite strong operational performance, shares experienced a premarket decline, potentially indicating that the market had already priced in the positive results or was focusing on valuation concerns. Management highlighted increased material input from priority suppliers and strategic acquisitions, such as CPP, to expand casting capacity and advance next-generation airfoil development.
Overall Takeaway
The Q3 2026 earnings call for GE Aerospace was broadly positive. The company delivered robust financial results that significantly beat analyst expectations and demonstrated strong momentum in order growth and commercial services, leading to a confident uplift in full-year guidance. While the market reaction showed some premarket share decline, possibly due to prior valuation run-ups, the underlying operational strength, healthy backlog, and strategic initiatives underscore a solid outlook for future performance.
|
|
Revenue
$14.1B
|
|
Net Income
$2.29B
|
|
Net Margin
16.21%
|
|
🔍 Deep Dive: PEGASYSTEMS INC
Period Ending 2026-09-30
|
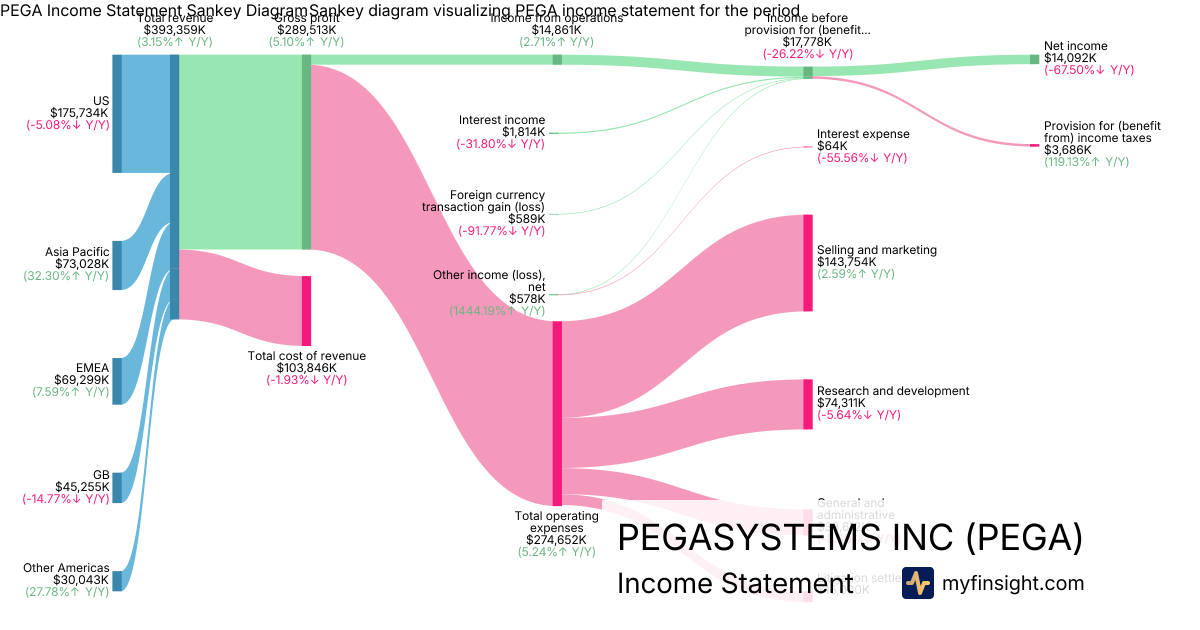
- Mixed Revenue Performance with Continued Cloud Growth: Pegasystems reported Q3 2026 total revenue of $393 million, an increase from the previous year. While Annual Contract Value (ACV) grew 6% year-over-year to $1.653 billion, Pega Cloud ACV continued its strong performance with 20% year-over-year growth to $219 million, highlighting a significant driver of future revenue.
- Decline in Net Profitability and EPS: Despite revenue growth, the company's Q3 2026 net income decreased significantly to $14.1 million from $43.4 million in the prior year, with diluted GAAP earnings per share falling to $0.08 from $0.24.
- Impact of Market Uncertainty and Sales Cycles: Management noted challenges in the first half of 2026, including customer uncertainty surrounding artificial intelligence and longer sales cycles, which impacted Annual Contract Value (ACV) growth. These factors have led to delayed deals, particularly in Q2.
- Strategic Focus on AI and High Operating Expenses: Pegasystems continues to emphasize its enterprise AI software for mission-critical work as a key strategic area. However, total operating expenses remained high at $275 million, including a notable $16 million litigation settlement and substantial selling and marketing costs of $144 million.
- Healthy Cash Position and Strong Deferred Revenue: The company maintains a solid financial position with $310 million in total cash, cash equivalents, and marketable securities, alongside robust deferred revenue of $429 million, indicating significant future revenue streams.
Overall Takeaway
The Q3 2026 earnings call for Pegasystems appears neutral to slightly negative. While the company demonstrated continued strong growth in Pega Cloud revenue and maintained a healthy cash position and deferred revenue balance, the significant year-over-year decline in net income and diluted EPS, coupled with management's acknowledgment of market uncertainty driven by AI and longer sales cycles, present headwinds for investors. The impact of high operating expenses and a notable litigation settlement also weighed on profitability.
|
|
Revenue
$393M
|
|
Net Income
$14.1M
|
|
Net Margin
3.58%
|
|
🔍 Deep Dive: Albertsons Companies, Inc.
Period Ending 2026-09-12
|
|
🚨 Price Alert: The stock price jumped by 7.42% around the earning call.
|
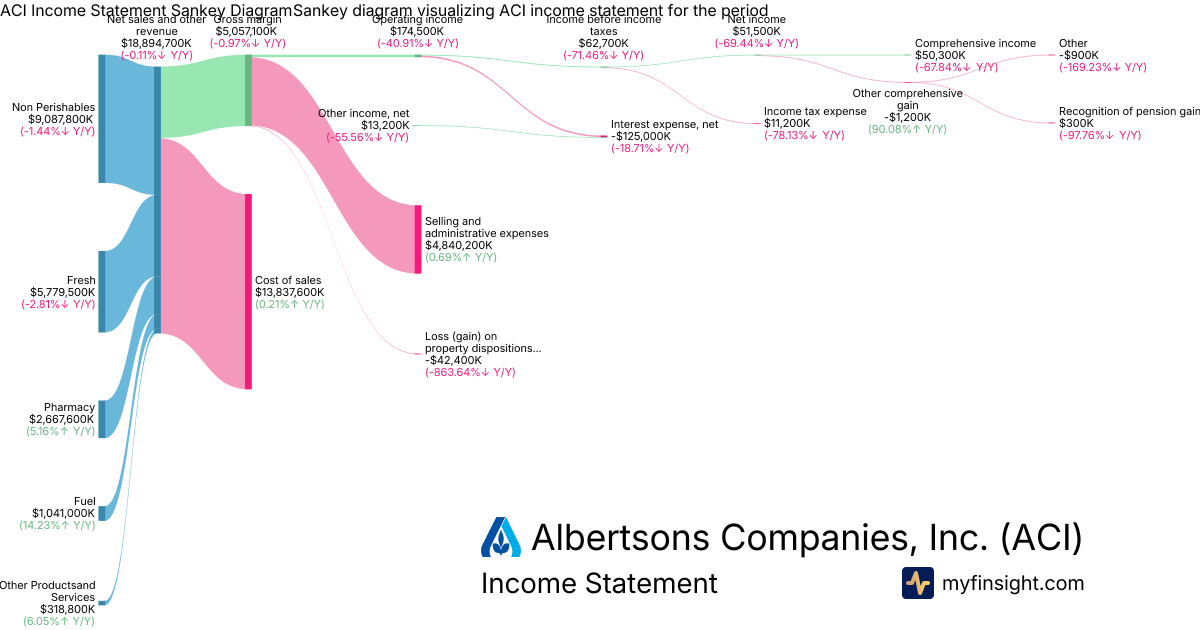
Albertsons Companies Inc. (ACI) has experienced significant stock price volatility around its recent earnings call, primarily driven by a mixed financial performance, a crucial strategic turnaround announcement, and prevailing macroeconomic headwinds. The company reported its Q2 2026 earnings on October 12, 2026, where it surpassed non-GAAP EPS estimates but faced flat sales and a substantial drop in net income. This performance, coupled with the withdrawal of full-year guidance and a new aggressive turnaround plan, has contributed to investor uncertainty and subsequent price fluctuations.
Key Factors Contributing to Volatility:
- Mixed Earnings and Withdrawn Outlook: ACI reported Q2 2026
net sales and other revenue
of
$18.9 billion
, which were flat year-on-year and in line with analyst expectations. However,
net income plunged to $51.5 million
, a significant decrease from the prior year. The company also withdrew its full-year financial outlook, signaling potential instability.
- Strategic Turnaround Initiative (ACI Edge): Management announced a comprehensive business review and the acceleration of its "ACI Edge" turnaround plan, aiming to simplify operations, reduce costs, and improve efficiency. While this plan seeks to address underlying issues, it also highlights the challenges the company faces in an intensely competitive market.
- Weakening Core Business and Market Share: Executive Chair Meg Whitman acknowledged persistent weakness in store traffic and units, attributing these to elevated fuel prices and ongoing inflationary pressures. The company's overall performance has not met expectations, with market share trends lagging and
gross margin
slipping to 26.8% from 27%.
- Macroeconomic Headwinds: Broader economic factors such as inflation, high fuel prices, and consumer trading down behavior continue to pressure the grocery sector, affecting ACI's sales and profitability.
- Analyst Downgrades: Following the earnings report, several prominent financial institutions, including Bank of America and Goldman Sachs, downgraded ACI's stock rating, citing concerns about near-term earnings pressure, operational complexity, and the competitive environment.
|
|
Revenue
$18.9B
|
|
Net Income
$50.3M
|
|
Net Margin
0.27%
|
|
🔍 Deep Dive: 3M CO
Period Ending 2026-09-30
|
|
🚨 Price Alert: The stock price jumped by 6.51% around the earning call.
|
3M (MMM) has recently experienced significant price volatility, primarily driven by a combination of a strong third-quarter earnings beat, an optimistic outlook with raised full-year guidance, and a strategic partnership with Amazon for optical connectivity in AI data centers.
Key Factors Contributing to Volatility:
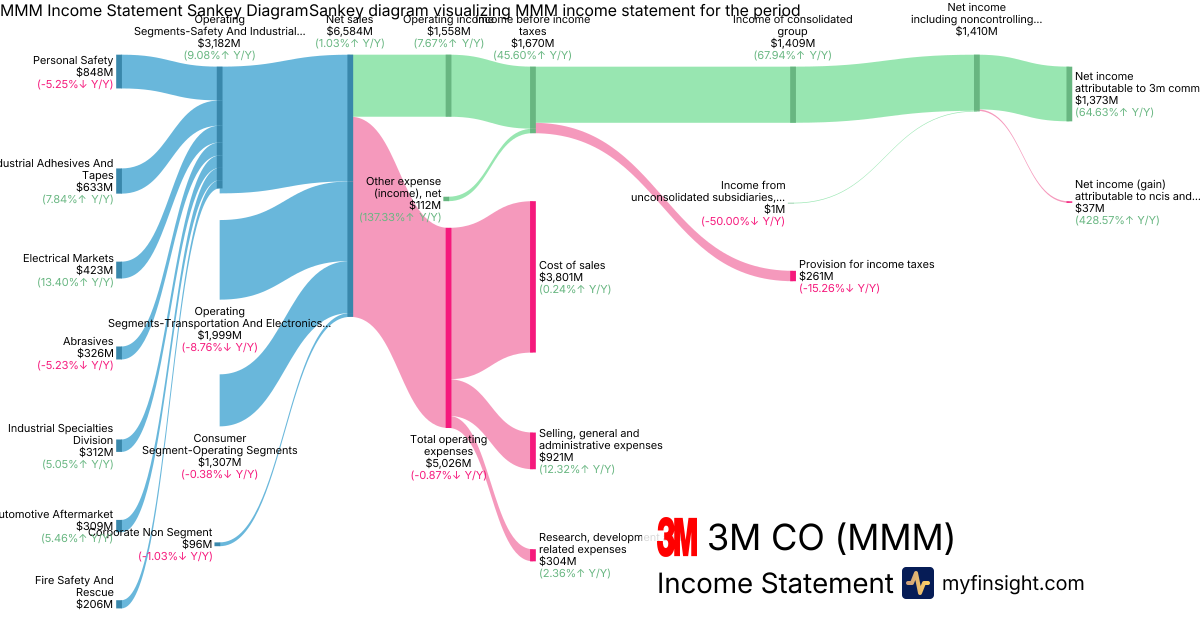
- Strong Q3 Earnings and Raised Full-Year Guidance: 3M reported adjusted earnings per share (EPS) of $2.50, surpassing analyst expectations, and subsequently raised its full-year adjusted EPS guidance to $9.10-$9.15. The company's net income attributable to 3M common shareholders was $1.37 billion.
- Strategic Amazon Partnership: A major catalyst was the announcement of an expanded commercial relationship with Amazon, including a warrant to acquire shares tied to achieving $6 billion in cumulative sales of optical connectivity and other data center products over seven years, which is expected to boost future net sales.
- Solid Organic Sales Growth: The company achieved 3.3% adjusted organic sales growth, contributing to total net sales of $6.58 billion for the quarter.
- Improved Operating Margin: Driven by productivity gains and structural transformations, 3M's adjusted operating margin expanded by 110 basis points to 26.2%, resulting in operating income of $1.56 billion.
- Robust Free Cash Flow Generation: 3M reported a strong adjusted free cash flow of $1.2 billion for the quarter, further solidifying its financial position and contributing to investor confidence.
|
|
Revenue
$6.58B
|
|
Net Income
$1.37B
|
|
Net Margin
20.85%
|
|
🔍 Deep Dive: FACTSET RESEARCH SYSTEMS INC
Period Ending 2026-08-31
|
|
🚨 Price Alert: The stock price jumped by 8.18% around the earning call.
|
FactSet (FDS) has recently experienced significant price fluctuations around its earnings call due to a confluence of factors, including mixed financial performance, strategic developments, and ongoing market dynamics. While the company reported an earnings per share (EPS) beat for the fourth quarter of fiscal year 2026, its full fiscal year net income saw a decline, presenting a complex picture for investors. This, combined with a focus on AI-led growth, client-side pressures, and balance sheet considerations, has contributed to investor re-evaluation and market volatility.
Key Factors Contributing to Volatility:
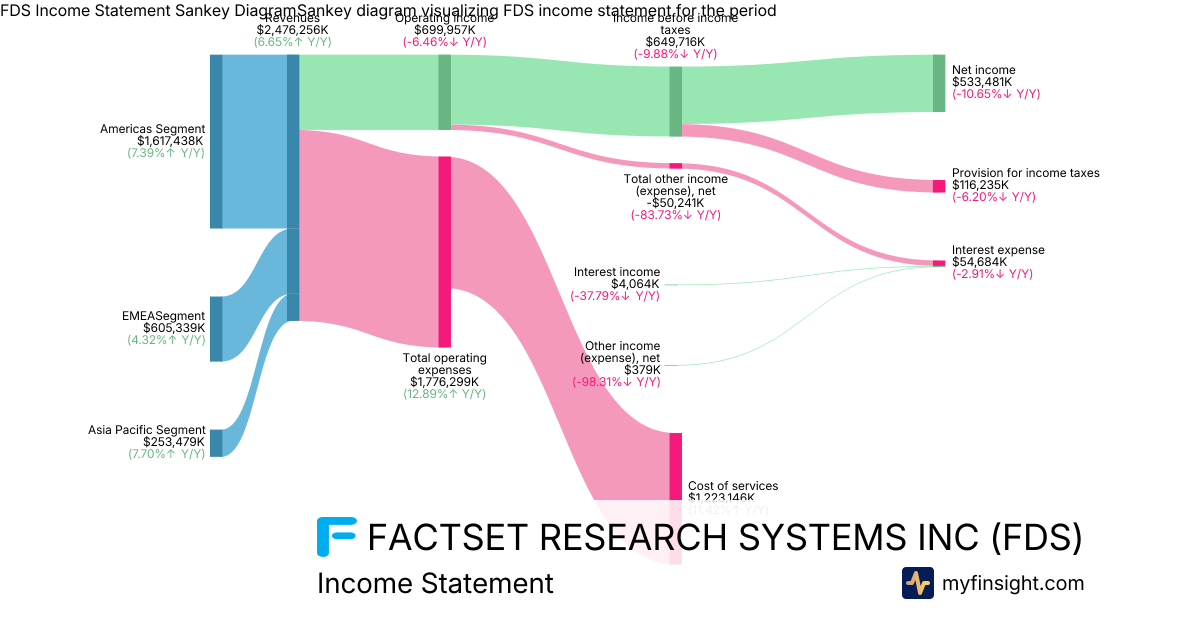
- Mixed Profitability Signals: Despite surpassing analyst expectations with a beat on Q4 2026 EPS, FactSet's net income for fiscal year 2026 experienced a 10.6% decline, resulting in a reported net income of $533 million.
- Substantial Revenue Generation and Operating Costs: FactSet demonstrated robust revenues of $2.48 billion, with a significant portion generated by its Americas segment. However, this was coupled with considerable total operating expenses of $1.78 billion, prompting scrutiny of operational efficiency.
- Strategic Investments Amidst Client Pressures: The company highlighted its commitment to AI-led growth and expanding partnerships in its earnings call. These strategic initiatives aim to bolster its operating income of $700 million, despite facing persistent headwinds from client cost-cutting and extended buying cycles.
- Balance Sheet Structure and Debt: FactSet's balance sheet indicates significant goodwill of $1.28 billion and net intangible assets of $1.85 billion. Investors are also noting the company's long-term debt of $871 million, particularly following recent changes to its debt facilities.
- Evolving Analyst Sentiment and Valuation: Recent analyst upgrades and price target raises for FDS suggest a growing confidence in the company's outlook. However, the stock has historically experienced volatility driven by market sentiment and valuation concerns, with past analyses indicating it was trading at a deep discount.
|
|
Revenue
$2.48B
|
|
Net Income
$533M
|
|
Net Margin
21.54%
|
|
🔍 Deep Dive: GENUINE PARTS CO
Period Ending 2026-09-30
|
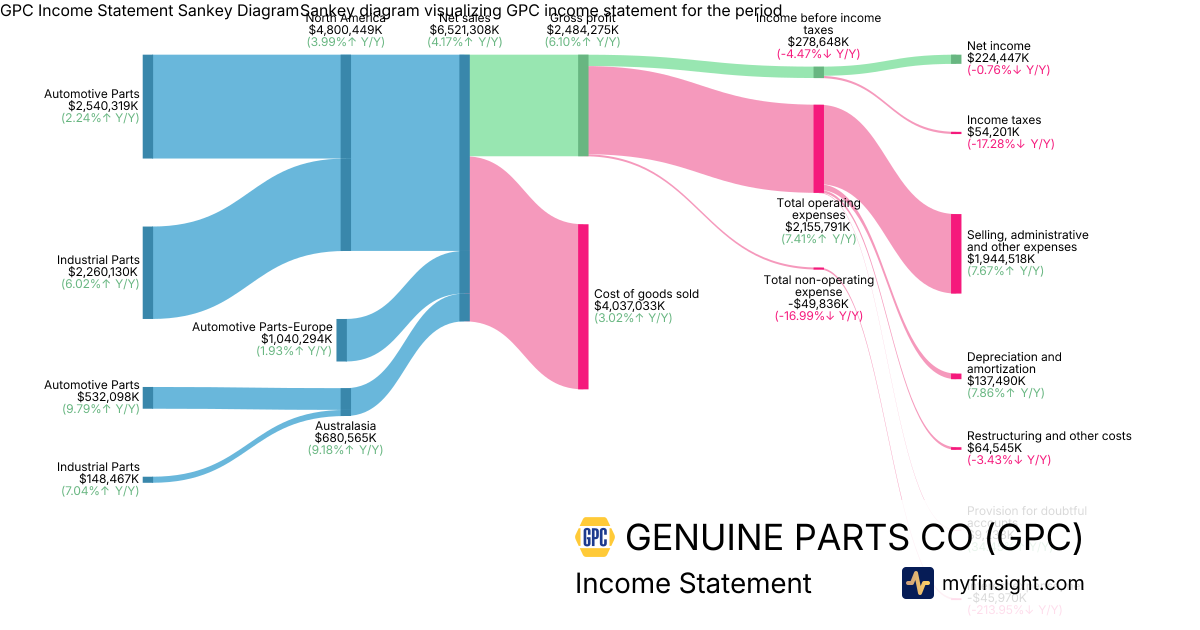
- Solid Revenue Growth: Genuine Parts Company reported Q3 2026 net sales of $6.52 billion, representing a 4.2% year-over-year increase, driven by a 2.9% comparable sales increase, 0.9% from acquisitions, and a 0.5% foreign exchange tailwind.
- Mixed Segment Performance with Industrial Strength: The Industrial Parts segment was a key growth driver, with sales reaching $2.41 billion and comparable sales increasing by 5.5%. In contrast, North America Automotive sales of $2.54 billion saw softer demand due to higher fuel costs and cautious consumer spending, leading to margin pressure.
- Gross Margin Expansion: The company achieved a 70 basis point expansion in its gross margin, reaching 38.1%, attributed to strategic pricing and sourcing initiatives.
- Narrowed EPS Guidance and Cost Pressures: While sales guidance was maintained, GPC narrowed its full-year 2026 adjusted EPS guidance to $7.50 to $7.75 (from $7.50 to $8.00). GAAP diluted EPS remained flat at $1.62 due to higher corporate, separation, and restructuring costs, including a $64.5 million impact from restructuring and other costs.
- Strategic Separation on Track: GPC remains on schedule to separate into two independent publicly traded companies, GPC and Motion, in the first quarter of 2027, with management highlighting important milestones achieved in this process.
Overall Takeaway
The Q3 2026 earnings call for GPC was neutral to slightly negative. While the company demonstrated solid top-line growth and strong performance in its Industrial segment, along with gross margin expansion, these positives were partially offset by softer demand and margin pressure in North America Automotive, elevated corporate and separation costs impacting GAAP earnings, and a narrowed full-year EPS guidance. The ongoing strategic separation provides a future catalyst, but current headwinds present challenges.
|
|
Revenue
$6.52B
|
|
Net Income
$224M
|
|
Net Margin
3.44%
|
|
🔍 Deep Dive: MSCI Inc.
Period Ending 2026-09-30
|
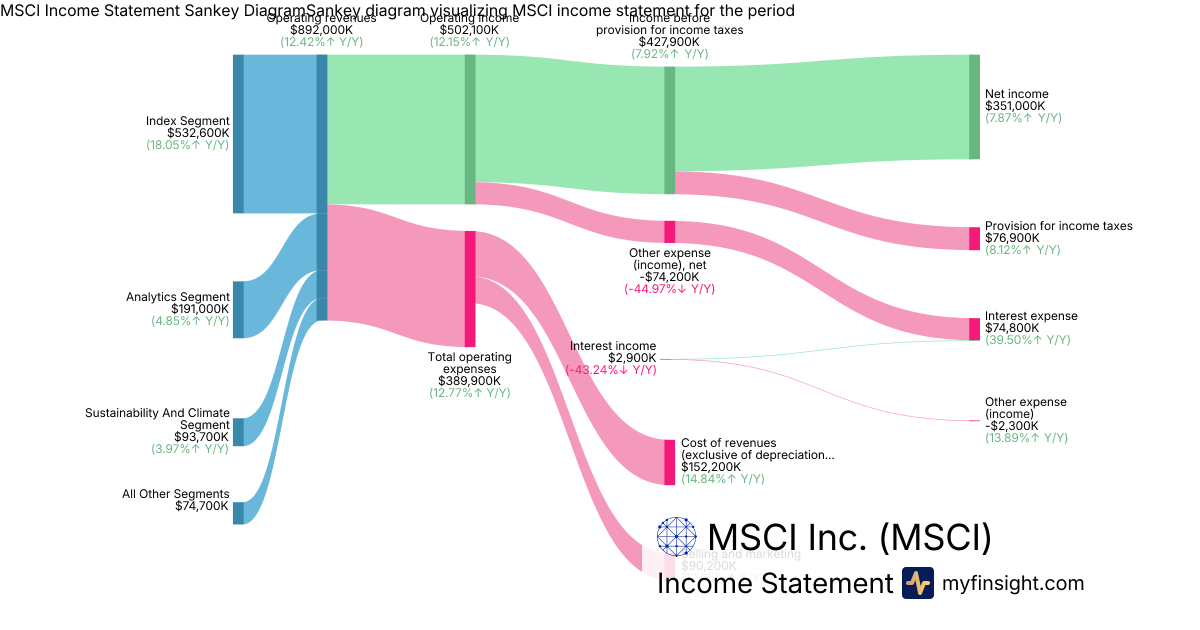
- Strong Financial Performance: MSCI reported robust operating revenues of $892 million, marking a 12.4% increase, and a net income of $351 million, up 14.4% year-over-year. Organic operating revenue also grew by 12.3%.
- Growth Driven by Index Segment and Asset-Based Fees: The Index Segment led revenue contribution with $533 million, an 18% year-over-year increase. Asset-based fees significantly surged by 24.9%, complementing a 7.7% rise in recurring subscription revenues, which totaled $624 million.
- Strategic Reinvestment in AI for Long-Term Growth: Management emphasized a strategic focus on AI-driven product innovation, including agentic solutions for private markets and a new model creation factory. CEO Henry Fernandez stated that the company plans to reinvest AI-driven efficiency gains into growth initiatives, aiming for significant long-term expansion rather than immediate margin expansion.
- Healthy Operating Profitability: The company demonstrated strong operational efficiency with an operating income of $502 million and an operating margin of 56.3%.
- Continued Shareholder Returns: MSCI's commitment to returning capital to shareholders was evident, with a significant amount of shares repurchased, reflected in its cumulative treasury stock at cost of $11 billion.
Overall Takeaway
The Q3 2026 earnings call for MSCI was broadly positive. The company delivered strong financial results, exceeding revenue and EPS expectations, driven by robust growth in its Index segment and a significant increase in asset-based fees. Management's strategic focus on reinvesting in AI-driven innovation for long-term growth, even at the expense of short-term margin expansion, signals confidence in future performance, while continued share repurchases highlight a commitment to shareholder returns.
|
|
Revenue
$892M
|
|
Net Income
$351M
|
|
Net Margin
39.35%
|
|
🔍 Deep Dive: EQUIFAX INC
Period Ending 2026-09-30
|
|
🚨 Price Alert: The stock price jumped by 19.83% around the earning call.
|
Equifax (EFX) experienced significant price movements around its Q3 2026 earnings call on October 20, 2026, with the stock rallying approximately 11% post-announcement. This volatility appears to be driven by a combination of better-than-expected adjusted earnings per share and resilient growth in diversified segments, which outweighed concerns stemming from a challenging U.S. mortgage market and mixed guidance. The market's positive reaction suggests relief as the impact of mortgage headwinds was quantified and contained, alongside strong underlying business performance.
Key Factors Contributing to Volatility and Post-Earnings Rally:
- Exceeded Adjusted EPS Estimates: Equifax reported adjusted diluted earnings per share of $2.26, surpassing the consensus analyst estimate of $2.20. Net income attributable to Equifax also rose by 32% year-over-year to $211.7 million.
- Strong Revenue Performance and Diversified Growth: The company posted $1.69 billion in operating revenue, a 10% year-over-year increase, meeting Wall Street forecasts. This growth was notably driven by its diversified markets, including a 7% rise in Workforce Solutions revenue to $693.9 million and a 13% increase in United States Consumer Information Solutions revenue to $599.1 million.
- Mitigated Mortgage Market Headwinds: Despite rising interest rates impacting the U.S. mortgage market, which led to a $20 million decline in Q3 U.S. mortgage revenue and a $60 million projected decline for Q4 compared to earlier guidance, the overall results demonstrated resilience.
- Improved Profitability and AI-Driven Productivity: Equifax's operating income was $355 million and the adjusted EBITDA margin expanded to 33.1%, with management highlighting AI and automation programs contributing to increased productivity.
- Strategic Expansion and Reassuring Guidance Elements: The company announced a $750 million acquisition of Círculo de Crédito to bolster its presence in Latin America. Although full-year revenue guidance was trimmed due to mortgage pressures, the raised full-year EBITDA margin guidance was interpreted by investors as a sign of operational strength.
|
|
Revenue
$1.69B
|
|
Net Income
$212M
|
|
Net Margin
12.51%
|
|
This newsletter is sent from
MyFinsight.com.
Was this email forwarded to you? Sign up here.
Unsubscribe
Copyright © 2026 MyFinsight, All rights reserved.
|