|
|
|
Daily Summary
|
November 17, 2026
|
Welcome to your daily digest. Today we are analyzing the latest income statements and filings from:
|
|
|
|
🔍 Deep Dive: Walt Disney Co
Period Ending 2026-10-03
|
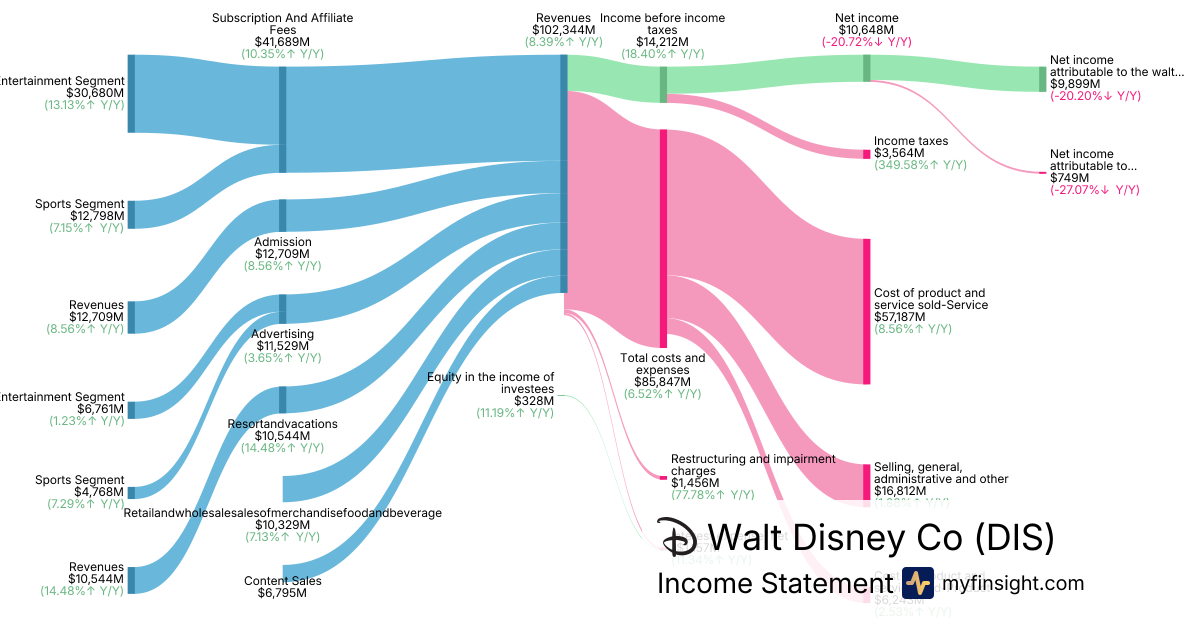
- Strong Revenue and EPS Growth: Disney reported a 6% increase in Q4 revenue to $22.6 billion and a 3% increase for the full year to $91.4 billion. Diluted EPS for Q4 increased 79% to $0.25, and for the full year, it more than doubled to $2.72.
- DTC Profitability Improvement: The company's combined Direct-to-Consumer (DTC) streaming businesses improved their profitability, achieving an operating income of $321 million in Q4. This marks significant progress, considering the business was losing over $4 billion two years ago.
- Experiences Segment Record Performance: The Experiences segment achieved record revenue and operating income for the full year. While Q4 operating income saw a 6% decline due to various factors, including pre-opening costs for new cruise line offerings and a decline in international parks, domestic parks saw growth driven by higher guest spending.
- Content Sales and Licensing Success: The Content Sales/Licensing and Other segment reported $316 million in operating income for Q4, boosted by the box office success of films like "Inside Out 2" and "Deadpool & Wolverine."
- Fiscal 2025 Outlook: Disney provided guidance for fiscal 2025, expecting high-single digit adjusted EPS growth, approximately $15 billion in cash provided by operations, and $8 billion in capital expenditures. They also target approximately $3 billion in stock repurchases and dividend growth tracking earnings growth.
Overall Takeaway
The earnings call was broadly positive. Disney demonstrated significant financial improvements, particularly in its streaming segment's profitability and overall revenue growth. The strong performance in content sales and the positive outlook for fiscal 2025, including projected EPS growth and capital returns to shareholders, suggest a company on a solid growth trajectory despite some segment-specific headwinds.
|
|
Revenue
$102B
|
|
Net Income
$9.9B
|
|
Net Margin
9.67%
|
|
🔍 Deep Dive: CISCO SYSTEMS, INC.
Period Ending 2026-10-24
|
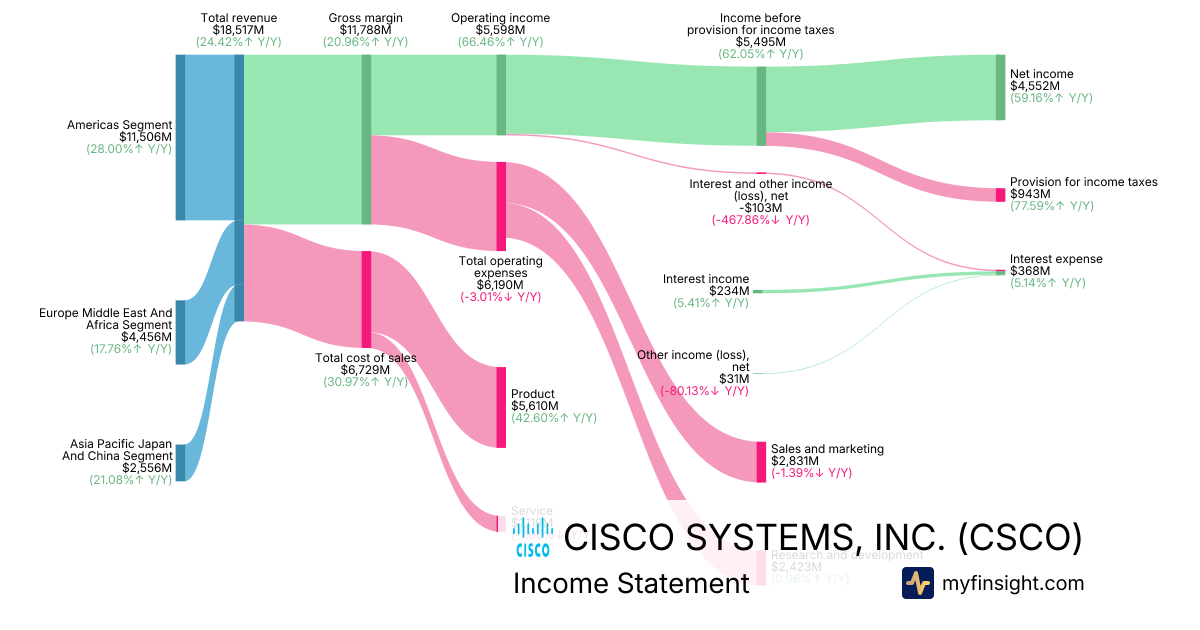
- Record Q1 FY27 Performance and Upbeat Guidance: Cisco reported record Q1 fiscal year 2027 revenue of $18.5 billion, a 24% year-over-year increase, significantly exceeding guidance and marking its strongest revenue growth in over 15 years. The company also raised its full-year fiscal 2027 revenue outlook to $74.8-$75.8 billion and non-GAAP EPS to $5.47-$5.53.
- Accelerated AI Infrastructure Demand: A key growth driver is the surging demand for AI infrastructure, with AI infrastructure revenue from hyperscalers now projected to reach $9 billion in fiscal year 2027, more than double the fiscal year 2026 total and representing 12% of total projected revenue.
- Strong Networking and Product Order Growth: The networking segment experienced a robust 43% year-over-year revenue surge, reaching $11.1 billion, extending its nine-quarter streak of double-digit growth. Overall product orders increased 21% year-over-year, indicating broad-based demand across all geographies and customer markets.
- Operational Efficiency Mitigates Margin Pressure: While non-GAAP gross margin declined 250 basis points year-over-year to 65.6% (with a reported gross profit of $11.8 billion), due to a higher hardware mix and elevated memory costs, non-GAAP operating margin increased to 37.8% (with operating income of $5.6 billion), reflecting strong operating leverage. Management expects full-year fiscal year 2027 operating margin to be 36%, with revenue per employee increasing by approximately 19% due to headcount reductions.
- Strategic Acquisitions and Security Focus: Cisco continues its strategic acquisition activities, notably completing the acquisition of WideField Security during the quarter to enhance its security offerings, especially in conjunction with Splunk for AI agent security. The security segment revenue grew 7% to $2.12 billion.
Overall Takeaway
The Q1 fiscal year 2027 earnings call was broadly positive. Cisco significantly exceeded market expectations with record revenue and EPS, driven by robust demand in AI infrastructure and a strong networking supercycle. The raised full-year guidance and demonstrated operational efficiency, despite gross margin pressures, underscore management's confidence in sustained growth and profitability.
|
|
Revenue
$18.5B
|
|
Net Income
$4.55B
|
|
Net Margin
24.58%
|
|
🔍 Deep Dive: F5, INC.
Period Ending 2026-09-30
|
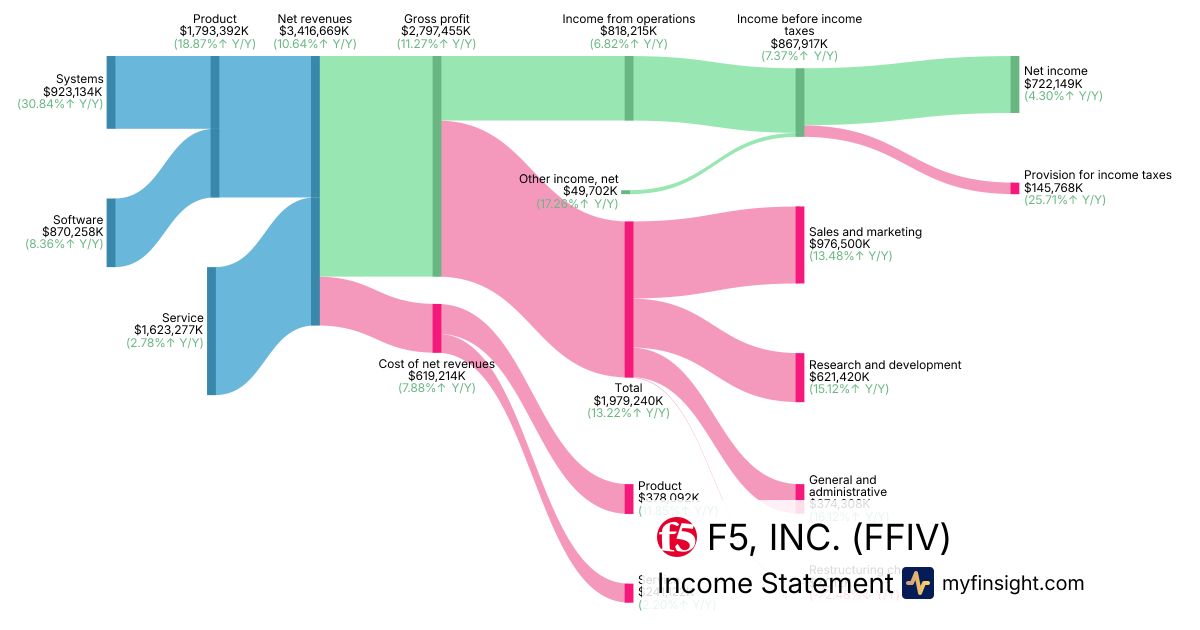
- Strong Fiscal Year 2026 Performance: F5 Networks reported robust full fiscal year 2026 net revenues of $3.42 billion, representing 11% annual growth, and a significant net income of $722 million. The company also surpassed Q4 2026 earnings per share estimates by 15.93%.
- Product-Led Revenue Growth and AI as a Key Driver: Full-year product revenue reached $1.79 billion, growing 19% year-over-year and outpacing service revenue of $1.62 billion. This growth was notably driven by demand for systems, software, and accelerating AI inference use cases, with direct AI bookings exceeding $100 million in fiscal year 2026.
- Solid Operational Profitability: F5 demonstrated healthy operational performance with a full fiscal year gross profit of $2.8 billion and income from operations of $818 million. However, operating expenses increased due to strategic investments in sales capacity and marketing, which pressured operating margins.
- Strong Future Revenue Visibility and Geographic Contribution: The company ended fiscal year 2026 with substantial deferred revenue, totaling approximately $1.27 billion (current) and $939 million (long-term), indicating a robust backlog and future revenue visibility. The Americas region continued to be the largest market, contributing $1.81 billion to overall revenue.
- Positive FY2027 Outlook and Strategic Investments: F5 provided guidance for fiscal year 2027 revenue growth of 8%-9%, supported by continued systems refresh, competitive takeouts, digital-sovereignty projects, and AI-related capacity expansion. The company is also undertaking a strategic inventory build to mitigate supply chain risks for fiscal year 2027.
Overall Takeaway
The Q4 fiscal 2026 earnings call for F5 Networks was broadly positive. The company delivered strong full-year financial results, particularly in revenue and net income, and exceeded Q4 earnings per share estimates. Positive guidance for fiscal year 2027, driven by strategic areas like AI and hybrid cloud, along with substantial deferred revenue, indicates a promising outlook, despite some short-term pressure on operating margins due to growth investments.
|
|
Revenue
$3.42B
|
|
Net Income
$722M
|
|
Net Margin
21.14%
|
|
This newsletter is sent from
MyFinsight.com.
Was this email forwarded to you? Sign up here.
Unsubscribe
Copyright © 2026 MyFinsight, All rights reserved.
|