🚨 Palo Alto Networks Inc, 🚨 Bath & Body Works, Inc., 🔗 VALVOLINE INC, 🔗 Air Products & Chemicals, Inc., 🚨 INTUIT INC.
|
|
|
Daily Summary
|
November 19, 2026
|
Welcome to your daily digest. Today we are analyzing the latest income statements and filings from:
|
|
|
|
🔍 Deep Dive: Palo Alto Networks Inc
Period Ending 2026-10-31
|
|
🚨 Price Alert: The stock price jumped by 8.17% around the earning call.
|
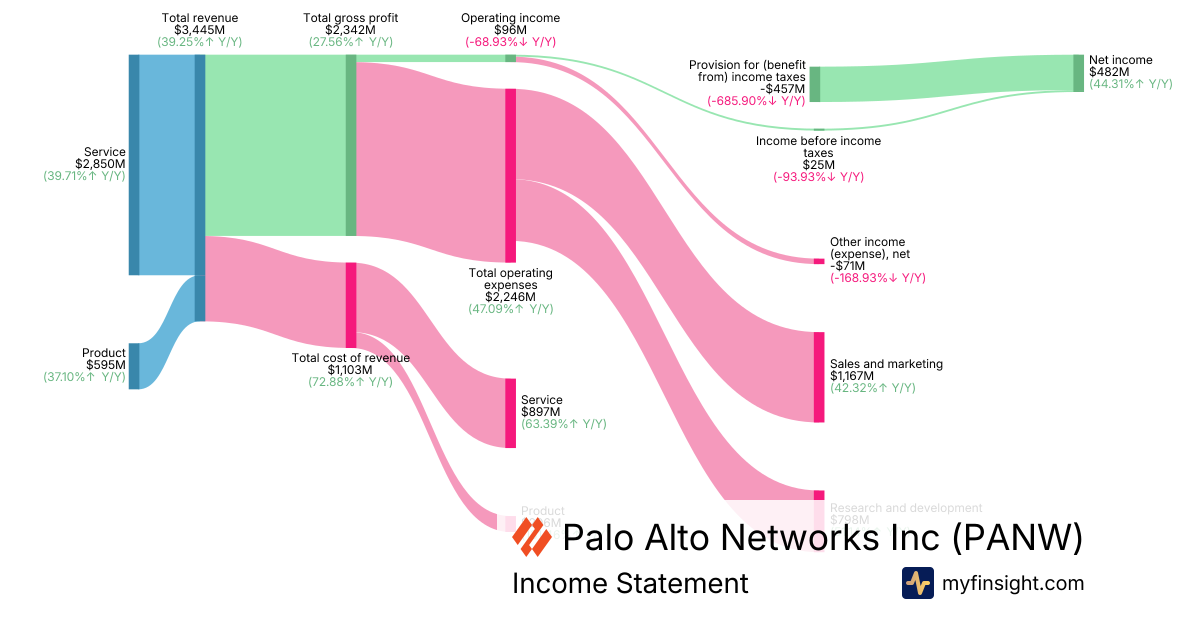
Palo Alto Networks (PANW) has recently experienced notable stock price fluctuations around its earnings call. This volatility appears to be driven by a combination of strong underlying revenue growth, particularly in its key security segments, coupled with the significant impact of non-operating items on net income and investor scrutiny on the efficiency of its substantial investments. The market seems to be weighing the company's robust future revenue visibility against the dynamics of its profitability drivers and debt structure.
Key Factors Contributing to Volatility:
|
|
Revenue
$3.44B
|
|
Net Income
$482M
|
|
Net Margin
13.99%
|
|
🔍 Deep Dive: Bath & Body Works, Inc.
Period Ending 2026-10-31
|
|
🚨 Price Alert: The stock price dropped by 12.94% around the earning call.
|
Bath & Body Works (BBWI) has recently experienced significant stock price volatility around its Q3 2026 earnings call, primarily driven by a cautious outlook for the crucial holiday season despite beating quarterly estimates, alongside persistent concerns over its highly leveraged balance sheet and broader retail headwinds.
Key Factors Contributing to Volatility:
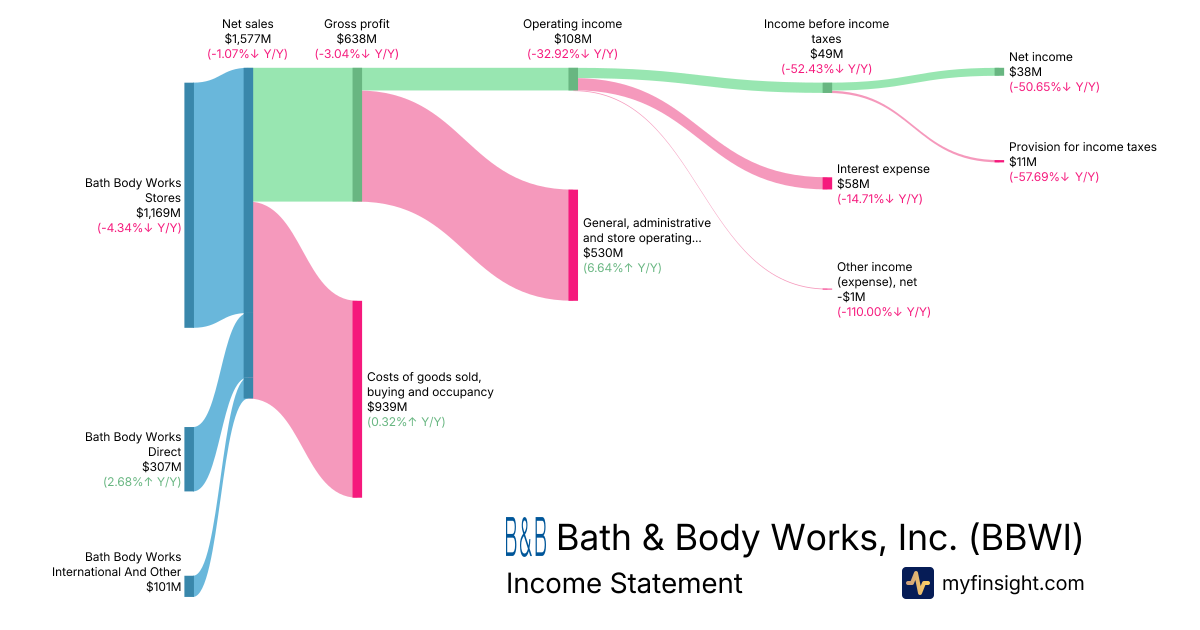
- Cautious Fourth-Quarter and Full-Year Outlook: Despite reporting Q3 2026 adjusted earnings per share of $0.26 and net sales of $1.58 billion that surpassed analyst expectations, the company's shares reacted negatively to a conservative forecast for the critical holiday fourth quarter. Management's guidance for Q4 net sales to decline between 5.5% and 2.0% and adjusted EPS of $1.41–$1.61 fell below analyst estimates, signaling potential challenges ahead.
- Persistent Sales and Profitability Declines: Bath & Body Works saw a 1.0% year-over-year decline in Q3 2026 net sales. Furthermore, net income significantly fell to $38 million from $77 million in the prior year, and operating income decreased to $108 million from $161 million, indicating ongoing pressures on the business's core performance.
- Highly Leveraged Balance Sheet: The company continues to carry a substantial long-term debt of $3.37 billion, which contributes to a negative total equity of -$1.11 billion and an accumulated deficit of -$1.26 billion. This highly leveraged financial position makes the stock particularly sensitive to market sentiment and concerns over solvency.
- Impact of High Operating and Interest Expenses: A considerable $58 million in interest expense, coupled with significant general, administrative, and store operating expenses of $530 million, heavily compresses the company's profitability. This financial structure means any slight miss in sales or increase in costs can severely impact net income.
- Challenging Retail Environment: Broader macroeconomic factors and competitive pressures continue to affect Bath & Body Works. Management highlighted ongoing concerns such as declining store traffic, consumer inflation, heightened competition, and rising input costs (including tariffs and crude oil prices) as significant headwinds impacting performance and future outlook.
|
|
Revenue
$1.58B
|
|
Net Income
$38M
|
|
Net Margin
2.41%
|
|
🔍 Deep Dive: VALVOLINE INC
Period Ending 2026-09-30
|
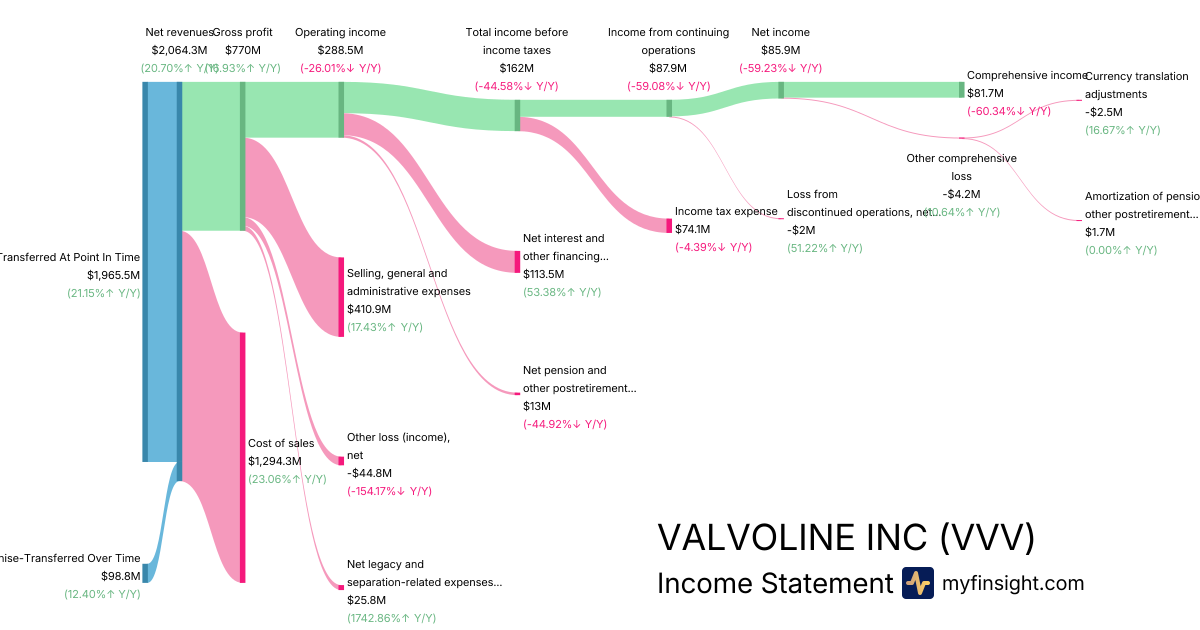
- Strong Q4 Performance and Full-Year Milestones: VVV reported robust Q4 net sales of $555 million, a 22% increase year-over-year, driven by 9.4% same-store sales growth and the contribution from the Breeze acquisition. For the full fiscal year, the company's net revenues reached $2.06 billion, with the Oil Changes segment contributing $1.53 billion, highlighting its role as a primary revenue driver. The company also celebrated its 20th consecutive year of same-store sales growth.
- Profitability and Margin Dynamics: Q4 adjusted EBITDA increased by 10% to $144 million, although the margin decreased by 280 basis points to 25.9%, primarily due to higher finished lubricant costs. Despite this, the company achieved a $770 million gross profit and $288 million in operating income. Q4 adjusted EPS of $0.42 was in line with expectations, while full-year adjusted EPS of $1.76 exceeded the top end of the guidance range.
- Significant Expenses Impacting Net Income: The reported net income of $85.9 million was notably reduced by considerable expenses, including $114 million in net interest and other financing expenses, and a substantial $74.1 million in income tax expense. Specific non-deductible items, such as $17.6 million related to the Breeze divestiture, influenced the tax rate.
- Strengthened Financial Position and Capital Allocation: VVV reported a healthy balance sheet with $163 million in cash and cash equivalents and $3.61 billion in total assets. The company made meaningful progress in strengthening its balance sheet by reducing leverage to 2.6 times net debt to adjusted EBITDA and announced plans to resume share repurchases under a $500 million authorization.
- Positive Fiscal 2027 Outlook: Management provided an optimistic outlook for fiscal 2027, projecting same-store sales growth of 5% to 7% and net sales in the range of $2.25 billion to $2.35 billion. Adjusted EBITDA is expected to be between $595 million and $625 million, with adjusted EPS forecast to be $1.85 to $2.05 per share.
Overall Takeaway
The recent earnings call for VVV was broadly positive. The company demonstrated strong performance in Q4 and achieved significant full-year milestones, including its 20th consecutive year of same-store sales growth and exceeding $4 billion in annual system-wide sales. While profitability was affected by elevated lubricant costs and substantial interest and tax expenses, VVV's financial position appears solid with reduced leverage and a commitment to shareholder returns through planned share repurchases. The positive fiscal 2027 guidance signals continued growth and confidence in future performance, which was generally well-received by investors.
|
|
Revenue
$2.06B
|
|
Net Income
$81.7M
|
|
Net Margin
3.96%
|
|
🔍 Deep Dive: Air Products & Chemicals, Inc.
Period Ending 2026-09-30
|
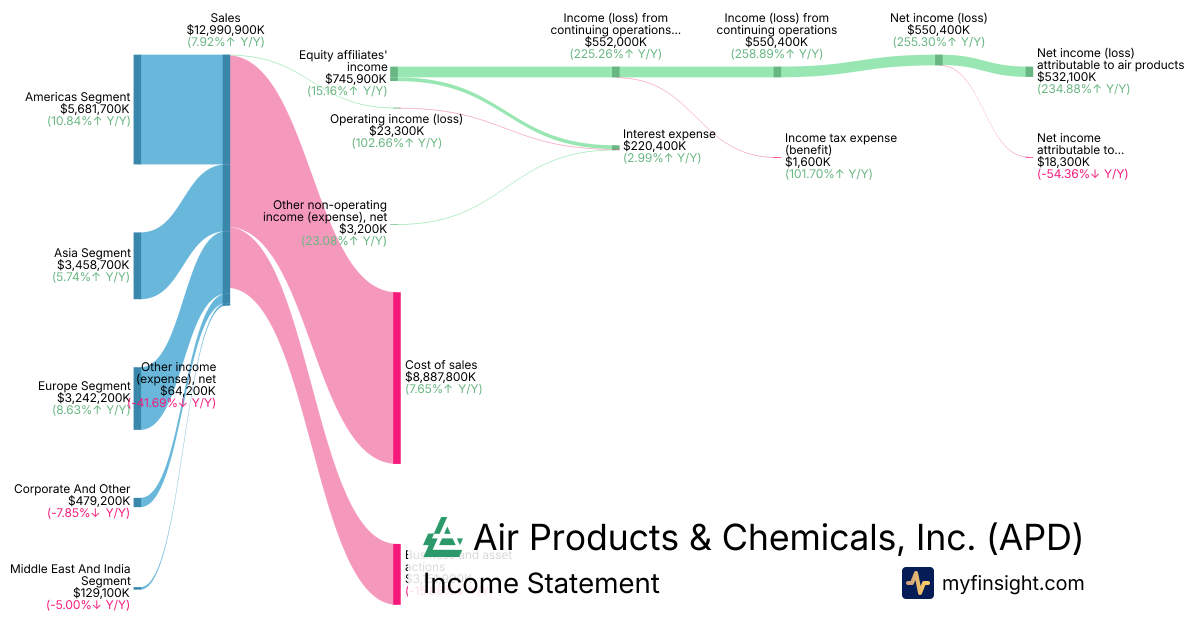
- Significant Impact from Business and Asset Actions: Air Products reported $3.15 billion in business and asset actions for fiscal year 2026, primarily related to project exit decisions, including two China coal gasification plants and the Louisiana Clean Energy Complex. This significantly impacted GAAP operating income, which was reported at $23 million for the full year.
- Resilient Net Income Driven by Equity Affiliates: Despite the substantial charges, net income attributable to Air Products was $532 million, largely supported by strong contributions from equity affiliates totaling $746 million. Adjusted EPS for fiscal 2026 increased 12% to $13.45, exceeding guidance.
- Solid Top-Line Revenue and Adjusted Operating Income Growth: The company achieved $13 billion in total sales for fiscal 2026, an 8% increase year-over-year. Adjusted operating income also increased 11% to $3.2 billion, primarily driven by higher on-site volumes, favorable currency, and higher non-helium pricing.
- Strategic Capital Allocation and Cost Reductions: Air Products reduced capital expenditures by $1.8 billion from the prior year and achieved approximately $95 million in savings from cost reductions in fiscal 2026. The company is pivoting capital towards a growing traditional industrial gas backlog, which expanded to approximately $3.3 billion.
- Positive Fiscal 2027 Guidance: For fiscal 2027, Air Products expects adjusted earnings per share in the range of $14.15 to $14.50, representing a 5% to 8% improvement from the prior year, driven by new assets, pricing, and productivity actions. Capital expenditures are projected to be between $3.0 billion to $3.5 billion.
Overall Takeaway
The recent earnings call for Air Products was broadly positive, despite significant non-GAAP charges related to project exits impacting reported GAAP operating income. The company demonstrated strong underlying operational performance with an 8% increase in sales and 12% growth in adjusted EPS, exceeding guidance. Management's strategic pivot away from speculative clean energy transition projects, coupled with disciplined capital allocation towards traditional industrial gas growth and cost reduction efforts, positions the company for continued adjusted earnings growth in fiscal 2027.
|
|
Revenue
$13B
|
|
Net Income
$532M
|
|
Net Margin
4.10%
|
|
🔍 Deep Dive: INTUIT INC.
Period Ending 2026-10-31
|
|
🚨 Price Alert: The stock price dropped by 9.52% around the earning call.
|
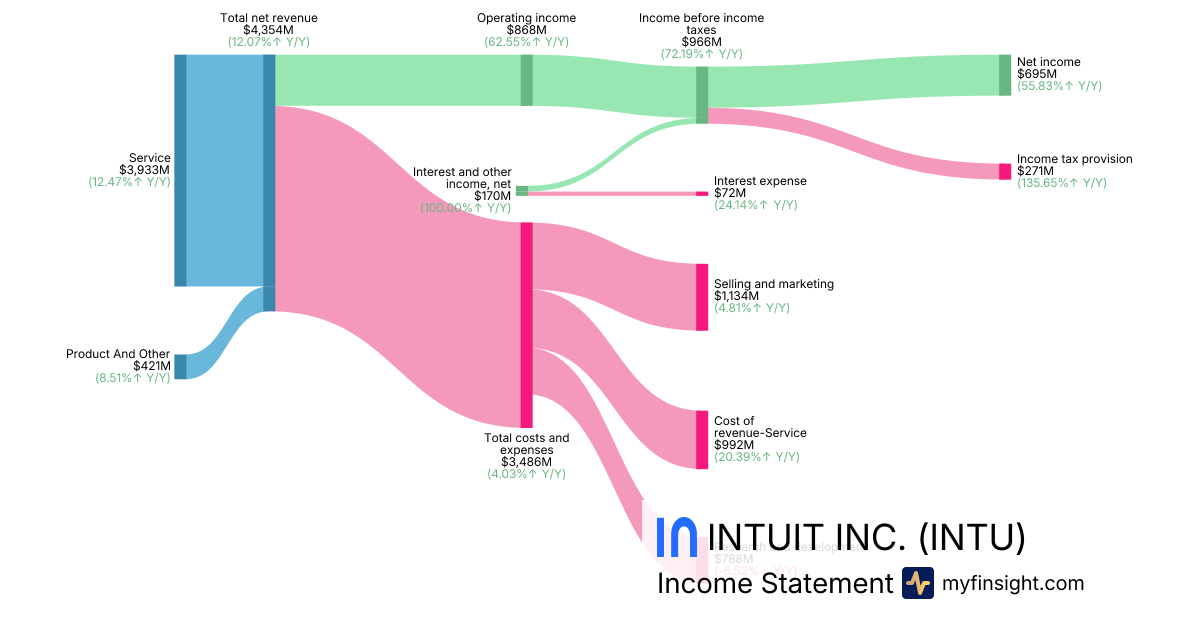
Intuit (INTU) recently experienced significant stock price fluctuations following its Q1 FY2027 earnings call, primarily driven by a mixed financial report. While the company surpassed analyst expectations for both revenue and earnings per share in the first quarter, its decision to lower full-year fiscal 2027 guidance and announce the divestiture of Mailchimp led to a negative market reaction.
Key Factors Contributing to Volatility:
- Q1 Earnings Beat Offset by Lowered Guidance: Intuit reported Q1 FY2027
total revenue of $4.35 billion, exceeding analyst estimates. However, the company subsequently lowered its full-year FY2027 revenue guidance below consensus, signaling a potential deceleration in growth.
- Softened Outlook for Consumer and Credit Karma Segments: A significant driver of concern was the reduced outlook for Consumer revenue growth, now projected at 2%-4% (down from 4%-6%), and a substantially lowered forecast for Credit Karma growth, estimated at 3%-7% (from 11%-13%). This downward revision was partly attributed to the prevailing interest rate environment.
- Mailchimp Divestiture: Intuit announced an agreement to sell its Mailchimp segment for approximately $3.68 billion, with the transaction expected to close in early 2027. Although the company plans to use the proceeds for share repurchases, the divestiture and a reported 1% decline in
Mailchimp's Q1 revenue of $313 million added an element of uncertainty regarding future portfolio composition.
- Strong Performance in Global Business Solutions: Despite the overall cautious outlook, the Global Business Solutions segment demonstrated robust growth, with
revenue increasing 15% to $3.08 billion in Q1 FY2027, driven by QuickBooks strength. The company also reported a
GAAP operating income of $868 million.
- Immediate Market Reaction: Following the earnings release, Intuit's stock experienced a sharp decline, falling over 9% in after-hours trading, as investors focused more on the conservative guidance and strategic changes rather than the positive Q1 performance.
|
|
Revenue
$4.35B
|
|
Net Income
$695M
|
|
Net Margin
15.96%
|
|
This newsletter is sent from
MyFinsight.com.
Was this email forwarded to you? Sign up here.
Unsubscribe
Copyright © 2026 MyFinsight, All rights reserved.
|